AI's $6.3 Trillion Funding Gap Is Bringing Back Financial Engineering
Marc Rubinstein argues that bond markets can't fund AI capex alone, and that the workarounds look a lot like 1870s railroad finance.
Why it matters · AI infrastructure is being paid for more and more with structured, off-balance-sheet debt. Knowing where that debt sits shows who carries the risk if the boom fades, and Rubinstein treats the volume of such deals as a sign of where we are in the cycle.
Big investment booms tend to bring a matching boom in financial engineering. In Net Interest, Marc Rubinstein argues that AI is following the pattern because the amounts involved leave no other option.
The size of the gap
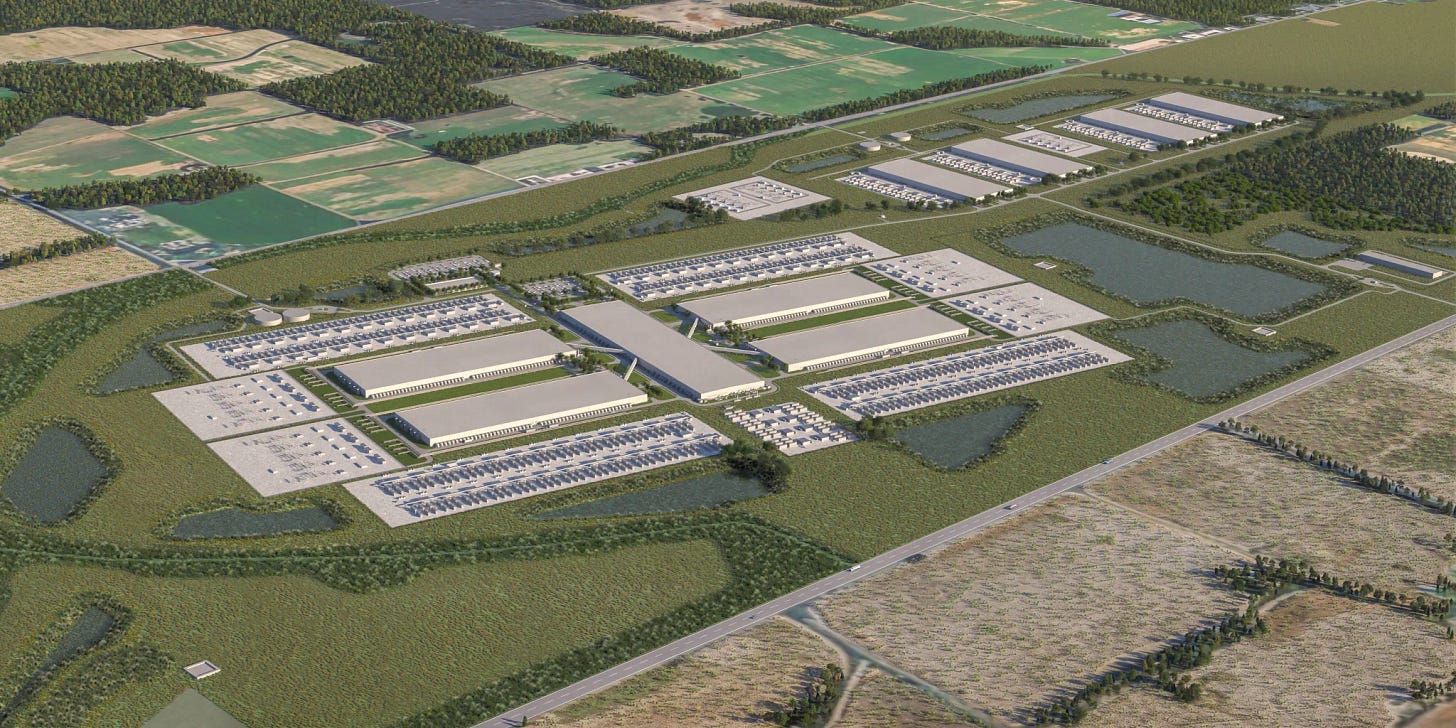
Estimates for AI infrastructure capex through 2030 run from $7.6 trillion to $8.0 trillion. KKR analysts think traditional US public investment-grade bond investors can supply about $1.7 trillion, which leaves a $6.3 trillion gap. KKR expects the rest to come from private investment-grade debt, asset-backed finance, infrastructure debt, structured solutions "and financing structures that may not even exist yet."
Rubinstein points to a historical parallel. AI capex could reach 3.63% of GDP through 2032. US railroad capex from 1870 to 1890 came to 2.24% of GDP. He quotes historian Richard White's Railroaded on how railroad investors moved from government bonds to secured bonds, then convertibles, first and second mortgage bonds, land grant bonds and income bonds. In White's words, these were "bonds on anything and everything that investors might accept as collateral," sold by bankers who acted like "carnival barkers."
What financial engineers do
Rubinstein admits financial engineering is hard to measure, but he says how much of it is going on is a useful signal of where we are in the cycle. It tends to thrive when ordinary balance sheets can't keep up with an investment boom. The same structures that keep the money flowing can also hide where risk is building up. The engineers' job is to satisfy companies, investors, regulators, auditors and rating agencies at once, splitting cash flows and risk among the parties most willing and able to carry them.