Today's stories ask who pays for new US generation: PJM's capacity crunch, solar tariffs, a big nuclear bet, New Mexico's gas fight and Google's Arkansas accounting.
Picked from 34 new articles across 13 sources · arrow keys for other days
Today in 30 seconds
30s left
Atlantic Council authors say PJM's price spikes call for long-term contracts, because default suppliers leaned on spot markets and nobody funded new plants. story 1 ↓
Solar PPA prices rose 4.9% to $64.23/MWh in Q3, and LevelTen expects Section 232 tariffs to add another $3–7/MWh. story 2 ↓
Prosperity One plans six large reactors totaling 6.6 GW at a former Kentucky coal site, built two at a time and feeding PJM. story 3 ↓
New Mexico hit its 2030 clean-power target six years early. Its biggest utility wants 1.7 GW of renewables plus a disputed 40 MW gas plant. story 4 ↓
Arkansas ratepayers paid construction charges on a $1.6B solar plant for Google. The amended Entergy deal changes that only from late 2028. story 5 ↓
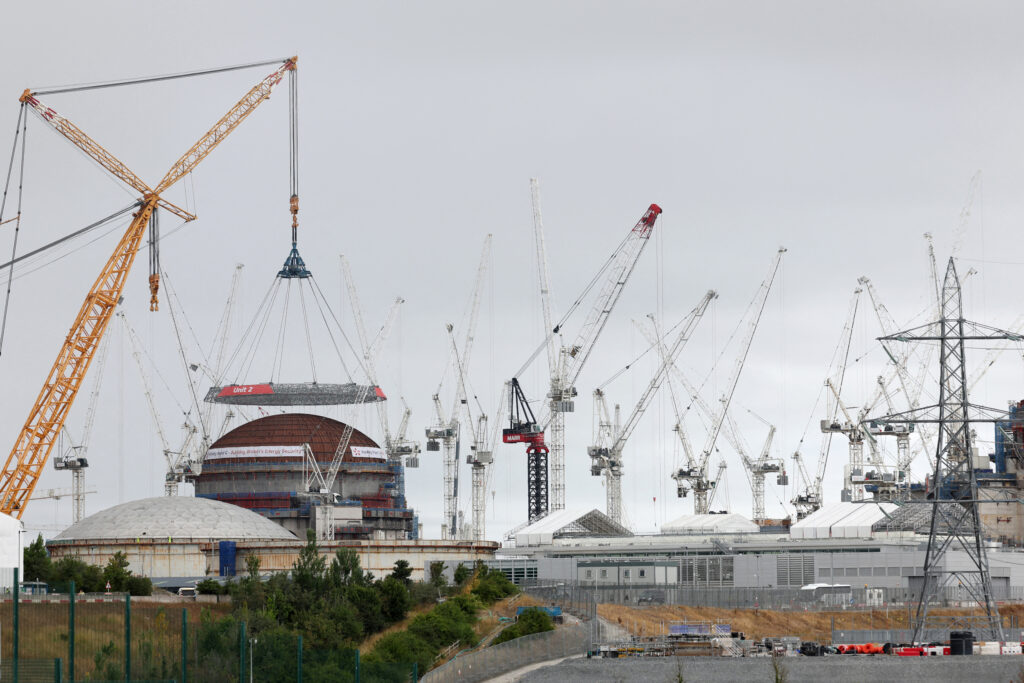
Britain is rewriting its nature rules for nuclear. Hinkley Point C's costly fish deterrent is expected to save fewer than one salmon.
1/5Utility Dive· Stephen Greene and Frank Willey· Oct 21
PJM's capacity price spikes call for long-term contracts, not re-regulation, authors argue
PJM's capacity auction has hit its price cap three times running and still fallen short of its reliability target. Two Atlantic Council analysts argue the fix is long-term power contracts, not a return to monopoly utilities.
Why it matters · PJM serves about 65 million people. Whether its states keep competitive markets or go back to regulated monopolies will decide who builds new power plants and who carries the risk.
Know this first
Context from the editor, not the article · 27 sec
1 · What a capacity market does
Some grid operators run auctions that pay generators to promise they will be available in a future year. The aim is to fund enough plants for peak demand, which energy sales alone may not pay for.
2 · PJM and restructured markets
PJM is the regional transmission organization that runs the grid and wholesale markets for 13 states and Washington, D.C. In these restructured states, utilities mostly own wires, not plants, and buy power from independent generators.
3 · Vertically integrated utilities
2/5Utility Dive· Emma Penrod· Oct 21
Solar power contract prices rise 4.9% as buyers race new US tariffs
LevelTen Energy says the average North American solar power contract rose 4.9% to $64.23 per megawatt-hour in the third quarter of 2026. Most of the rise came from new and upcoming import tariffs.
Why it matters · Long-term power contract prices show what new clean power costs to build. Tariffs, permitting delays and expiring tax credits are pushing those costs up together.
Know this first
Context from the editor, not the article · 29 sec
1 · What a PPA is
A power purchase agreement (PPA) is a long-term contract in which a buyer, often a large company, agrees to pay a fixed price per megawatt-hour for a project's output. These contracts often help finance new wind and solar farms.
2 · Who LevelTen is
LevelTen Energy runs an online marketplace where developers offer PPAs and buyers bid on them. Its quarterly price index is built from those offers and is one of the most widely cited benchmarks for renewable contract prices in North America.
3 · Section 232 tariffs
Section 232 of the Trade Expansion Act of 1962 lets the US president impose import tariffs on national-security grounds. The administration announced new 232 tariffs in August 2026 that affect solar and wind equipment.
3/5Heatmap· Alexander C. Kaufman· Oct 21
Nuclear startup plans six large reactors at a former coal site in Kentucky
The Nuclear Company, a startup staffed by former managers of Georgia's Plant Vogtle, plans up to six large Westinghouse AP1000 reactors in Kentucky. It is betting that building one design over and over will cut costs.
Why it matters · Most U.S. nuclear hopes rest on small, unproven reactors. This project is a test of whether repeating a large, already-built design at one new site can get costs down.
Know this first
Context from the editor, not the article · 26 sec
1 · The Vogtle overrun
Plant Vogtle in Georgia got the first two AP1000s, Westinghouse's 1.1-gigawatt pressurized water reactor. They took about 15 years to finish and ran billions over budget, which scared U.S. utilities away from large reactors.
2 · Large versus small reactors
Much of the U.S. industry now backs small modular reactors (SMRs). The idea is that factory-built small units will be cheaper. No SMR has been built commercially in the U.S. yet, so nobody knows its costs.
3 · Learning by repetition
Building the same design again usually costs less, because crews, managers and suppliers learn from each unit. China did this with the AP1000 and with its own Hualong One reactor.
4/5Canary Media· Julian Spector· Oct 21
New Mexico hit its 2030 clean-power target six years early
New Mexico's utilities reached 50% renewable electricity in 2024, six years ahead of the state's 2030 deadline. The largest, PNM, says it can keep going, but only if regulators let it build a small new gas plant.
Why it matters · New Mexico has reached the point where adding cheap wind and solar stops being enough, and its fight over a small gas plant shows what many grids will face next.
Know this first
Context from the editor, not the article · 27 sec
1 · New Mexico's 2019 law
The Energy Transition Act requires the state's investor-owned utilities to reach 50% renewable electricity by 2030 and 80% by 2040, then become 100% carbon-free by 2045. Under the 2045 goal, nuclear counts as clean.
2 · Nameplate versus firm power
Nameplate capacity is a plant's maximum output. Wind and solar rarely run at that maximum and can't be turned on when needed, so a grid needs far more nameplate capacity than its peak demand.
3 · Resource adequacy
This is a utility's obligation to have enough generation available to meet demand in every hour, including rare bad cases such as a cloudy, windless evening at peak load. Regulators enforce it with planning metrics.
5/5Latitude Media· Maeve Allsup· Oct 21
Google and Entergy rework the accounting behind an Arkansas data center deal
Entergy Arkansas and Google amended their data center power deal after customers were billed for a solar plant Google's payments more than cover. Future projects won't use that billing route, but most contract terms stay sealed.
Why it matters · Who pays to build power for data centers, and when, is turning into a big fight over electricity bills. Accounting choices like this one decide whether existing customers carry the cost up front.
Know this first
Context from the editor, not the article · 31 sec
1 · How utilities earn money
Regulated utilities earn an approved return on the capital they invest in plants, called the rate base. If someone else pays for part of a plant, the rate base shrinks, and so does the utility's profit.
2 · Paying during construction
Normally customers start paying for a plant once it operates, through base rates set in rate cases. Some states let utilities bill customers for financing costs while the plant is still being built, often through a separate line item called a rider.
3 · Data centers as large loads
Hyperscalers like Google need hundreds of megawatts for each campus. Utilities sign special contracts with them, and the question is whether new plants built for them push costs onto other customers or spread fixed costs and lower everyone's rates.
The alternative model is a regulated monopoly that owns generation, transmission and distribution. Regulators approve its investments and let it earn a set return on them, which rewards building capital assets.
Image: Utility Dive
1, the grid operator for 13 states and Washington, D.C., has now seen its 2 clear at the price cap approved by the Federal Energy Regulatory Commission (3) three times in a row. The latest auction's price was more than eleven times what it was four years ago, and it still didn't buy enough capacity to meet PJM's reliability requirement. A capacity auction pays power plants to commit to being available in a future year.
Some observers now want restructured states to go back to 4, meaning regulated monopolies that own power plants as well as wires. In a Utility Dive op-ed, Frank Willey and Stephen Greene of the Atlantic Council's Global Energy Center argue that this mistakes a flaw in how markets were set up for a failure of competition itself.
Where they say it went wrong
Their diagnosis centers on retail supply. Thirteen states plus D.C. let households choose a competitive supplier, but they also offer an attractive default service, so only about 25% of residential customers outside Texas had switched as of 2024 (according to the Energy Information Administration, EIA). Regulators often required rate cuts of 10% to 20% when restructuring began, and they encouraged default providers to buy heavily on the 5 (short-term purchases at current prices) instead of locking in long-term supply.
While demand growth was slow, that cost little. Now demand is accelerating, and nobody holds the long-term contracts that would protect customers from price swings and give developers revenue they can count on.
Why spot prices don't get plants built
The authors make a simple financial point. A plant built today at high cost has to recover that cost over decades. A price spike that will probably fade within a few years can't support that investment, so high capacity prices alone don't produce new supply.
What they propose
They point out that the original market designers expected utilities and other retail suppliers, called 6, to buy most of their power through contracts. 7 markets were only meant to handle transmission limits and real-time imbalances. Steel, grain and chemicals trade the same way, with a mix of contracts and spot purchases.
Building on a recent PJM white paper, they suggest two routes:
Bilateral contracts between 8 and LSEs, required through state hedging mandates.
RTO-brokered contracts paid for by a reliability charge on market participants.
Buyers would hold overlapping contracts signed at different times, so deals struck at today's shortage prices get averaged with cheaper ones later.
What's missing
This is an argument, not an analysis. The piece gives no estimate of how quickly contracts would bring new capacity online. It also leaves open who would set the contracted quantities, and how that differs from regulators planning supply under another name.
1 is the regional transmission organization (2) that runs the grid and wholesale power markets for 13 states and Washington, D.C. Its 3 has now cleared at the price cap approved by the Federal Energy Regulatory Commission (4) for the third auction in a row. The latest price was more than eleven times what it was four years ago, and the auction still procured less than PJM's reliability requirement. Capacity auctions pay generators to commit to being available in a future delivery year, so a shortfall at the cap tells you that higher prices did not draw in enough supply.
Those results have revived calls for restructured states to return to 5, which are regulated monopolies that own generation along with transmission and distribution. In an op-ed in Utility Dive, Frank Willey, an assistant director at the Atlantic Council's Global Energy Center, and Stephen Greene, a nonresident senior fellow there, argue against that move. In their view the crisis comes from how competitive markets were set up, not from competition itself.
How the markets were built
The authors list the steps that created competitive wholesale markets:
1978: The Public Utility Regulatory Policies Act (PURPA) required utilities to buy power from qualifying independent generators. The price was the utility's "avoided cost", meaning what it would otherwise have paid to generate or buy that power.
1992: The Energy Policy Act let FERC order utilities, case by case, to open their transmission lines to others.
1996: FERC Orders 888 and 889 made open, non-discriminatory transmission access a requirement for public utilities and set rules on conduct and information sharing.
1999: FERC Order 2000 set up the framework for RTOs, PJM among them.
Restructuring, they write, had two goals. One was competition in generation and retail sales. The other was to remove the bias of regulated utilities toward over-investing in capital assets, since rate-of-return regulation lets a utility earn more by building more. They say both goals have been met and that customers have benefited over two decades.
The retail flaw
Retail competition is where the authors place the problem. Thirteen states and D.C. offer residential electricity choice. Each also has a default provider whose terms are attractive enough that, according to Energy Information Administration (EIA) data, only about 25% of residential customers outside Texas used a competitive supplier in 2024.
They say this was partly a political choice. To show that restructuring lowered bills quickly, utility commissions often mandated rate cuts of 10% to 20% at launch. Many states also nudged default providers to rely heavily on the 6 rather than signing long-term supply deals. The authors cite academic work arguing that the result was a structural subsidy, with regulated transmission and distribution service subsidizing the cost of default retail supply.
While demand growth stayed low, nobody noticed the risk. The missing contracts are hedges. They would have shielded customers from volatile wholesale prices and given generators predictable revenue, and that predictability lowers financing costs and makes new plants cheaper to build. Once demand started growing quickly, the gap showed up as price spikes.
Why spikes don't build plants
The central mechanism in the piece is investment arithmetic. A developer building today faces high costs that must be paid back over the life of the plant, often decades. Under the current structure, the market prices available to that plant are likely to fall back to normal within a few years. A short window of high prices can't repay a long-lived, expensive asset, so the authors see no business case for building on the strength of a spike.
As an illustration of the logic (these numbers are not from the article): suppose a plant needs a stable payment for 20 years to pay off its cost, and the market pays a high price for three years and a low price afterwards. The developer has to value the plant on the full 20-year stream, not on the three good years. A contract that guarantees the stable payment is what makes the project financeable.
The authors grant that a market running entirely on spot prices would work in theory. They argue the extreme prices it would need are not acceptable in practice. They note that even Texas, where shortages can push spot energy prices very high, has a retail structure that pushes providers to hedge with contracts.
"Market" means more than the RTO exchange
Willey and Greene argue that the people who designed these markets never meant for everything to run through central RTO spot markets. The plan was for sophisticated 7, the utilities and retailers that serve end customers, to buy power from sophisticated generators. RTO markets would handle transmission constraints and the imbalances that show up close to or in real time.
They compare this to steel, grain and bulk chemicals. In those markets buyers and sellers use long-term contracts to keep supply and demand roughly matched and use spot purchases to adjust in the short term. Neither goal of restructuring, they say, required giving up contracts or leaving consumers exposed to spot prices.
The proposal
Following a recent PJM white paper, the authors back rebuilding a long-term contracting layer, using either of two routes or both:
Bilateral power purchase agreements between 8 (IPPs) and LSEs, driven by hedging requirements that state regulators impose.
Contracts between IPPs and the RTO itself, funded through a reliability charge on market participants.
In both cases independent developers still compete to offer projects and still carry the risk of building them. The authors call this restoring a layer that was dropped, using tools that already exist, rather than redesigning the market.
They also describe how a prudent buyer would manage the contracts: hold a portfolio of overlapping agreements signed at different times. Contracts signed now at shortage prices would then be averaged against contracts signed later, when new capacity is cheaper. Spot markets would remain to settle the difference between what was contracted and what is actually needed at delivery.
What the piece leaves open
This is an argument from two policy analysts, not new data or modeling. It gives no estimate of how much capacity a contracting mandate would bring in or how fast, and no estimate of what it would cost consumers compared with today's capped auctions.
Several design questions also go unanswered:
Who decides how much each LSE must hedge, and for how many years?
Would an RTO-run reliability charge end up looking much like central planning, the thing restructuring was meant to replace?
How does contracting get around what actually limits new supply? The piece doesn't address interconnection queues, permitting or equipment lead times, which are commonly cited as reasons PJM capacity is slow to arrive whatever the price signal.
The authors don't claim that contracts would solve those problems. Their narrower claim is that contracts give developers a price signal they can finance and that a spot spike can't.
Remember
Only about 25% of residential customers in retail-choice states outside Texas had left their default supplier as of 2024.
Default suppliers' reliance on spot purchases meant nobody signed the long contracts that finance new plants.
The authors' proposal leaves developers competing and carrying build risk. Regulators or PJM would require the hedging.
Workers build solar panels at a factory in Turkey. Imported modules like these face the new US tariffs.
The news
The average North American solar 1 rose 4.9% in the third quarter of 2026, to $64.23 per megawatt-hour (MWh). A PPA is a long-term contract to buy a project's output at a fixed price. The data come from 2, which runs a marketplace for these contracts. Solar is up 6% from a year ago and 12.7% since Q3 2024.
Wind PPAs held roughly flat this quarter, but they are up 13.8% year over year and 27.5% since 2024.
Tariffs, priced in early
Sarah Wolf, LevelTen's director of North America transactions, says tariffs caused most of the increase. The main one is a new round under 3, a trade law that lets the president tax imports on national-security grounds. These tariffs were announced in August and start later this year. Wolf expects them to add another $3–7/MWh, about 5–11% on today's average (our arithmetic).
Much of the Q3 jump is buyers rushing to sign before the tariffs apply. Developers can't soften the blow by stockpiling, because current rules forbid stockpiling solar modules. "We're already seeing more than half of solar modules repriced," Wolf said.
Wind: flat on average, rising almost everywhere
Wind prices kept climbing across most of the US. A modest drop in Texas pulled the average down. That region's grid is run by 4, the Electric Reliability Council of Texas. More wind has come online there recently, and buyers see solar as politically safer. Elsewhere, federal permitting problems have shrunk supply. "We have much less wind than we have ever seen getting onto the platform," Wolf said.
5 crowd out other buyers
Hyperscalers, the biggest cloud and AI data-center operators, took 99% of new-build PPAs signed in Q1 2026, Wolf said. The 6 reports that first-time PPA buyers are at their lowest level since 2016.
Other buyers are signing contracts with older wind and solar projects whose original contracts have expired. Some developers are also 7 (re-equipping) or expanding existing sites. Wolf says these deals cost about the same as new-build ones.
What comes next
Wolf expects prices to keep rising, citing geopolitical uncertainty and expiring federal renewable tax credits. Projects must meet deadlines to qualify, so "it's still a matter of racing against the clock," she said.
The article doesn't say how much of the rise is the rush to sign early and how much is real equipment cost. LevelTen's index also reflects offers on its own platform, not the whole market.
The numbers
The average North American solar 1 rose 4.9% in the third quarter of 2026, to $64.23 per megawatt-hour (MWh). A PPA is a long-term contract to buy a project's output at a fixed price. The figures come from 2, which runs a marketplace where developers list PPA offers and buyers bid on them. Solar prices are up 6% from a year earlier and 12.7% from Q3 2024. Working backwards from those percentages (our arithmetic, not LevelTen's), the average was about $61/MWh last quarter and about $57/MWh two years ago.
Wind PPAs held roughly flat this quarter, but they are up 13.8% year over year and 27.5% since 2024. The article doesn't give wind's dollar level. Over two years, wind contracts have risen about twice as fast as solar.
Why solar jumped: tariffs, mostly in advance
Sarah Wolf, LevelTen's director of North America transactions, says tariffs drove most of the recent increase. The main one is a new round under 3, a 1962 trade law that lets the president tax imports on national-security grounds. These tariffs were announced in early August and take effect later this year. Wolf estimates they could add $3 to $7/MWh to PPA prices once they apply. Against today's average, that is roughly another 5–11% (our calculation).
Much of the Q3 rise is anticipatory, Wolf says. Buyers are rushing to sign before the tariffs bite, and the extra demand lifts prices. Developers can't fully protect themselves, because current rules bar them from stockpiling solar modules ahead of the tariffs. Equipment costs are already moving. "We're already seeing more than half of solar modules repriced," Wolf said, and those costs pass to sellers and then to buyers.
Why wind looks flat but isn't
The flat wind average hides a split. LevelTen says wind PPA prices kept rising across most of the US. The exception was territory run by 4 (the Electric Reliability Council of Texas, which operates most of the Texas grid). A modest drop there pulled the North American average down.
Wolf gives two reasons for Texas. More wind projects have come online in ERCOT in recent months than in other regions. Demand for wind has also cooled because buyers see solar as "a safer bet in the current political landscape." Elsewhere, the limit is supply. Federal permitting problems have left very few new-build wind projects. "We have much less wind than we have ever seen getting onto the platform because of the challenges with permitting," she said.
Who is buying: hyperscalers take almost everything
Demand from hyperscalers, the largest cloud and AI data-center operators, is reshaping the market. Wolf said 99% of new-build PPAs signed in Q1 2026 went to hyperscalers. The 5 (CEBA), a trade group for corporate clean-power buyers, reports that first-time PPA buyers are at their lowest level since 2016. In effect, a handful of tech companies with very large power needs now take nearly all contracts for new projects.
A side door: older projects
Smaller buyers have found another option. As the US renewable fleet ages, some older wind and solar projects have reached the end of their original contracts, and their output is available to new bidders. Some developers are also 6 existing sites (replacing old turbines or panels with newer equipment) or expanding them, instead of or alongside building new projects.
7 mostly want new-build contracts. Buying from new projects lets them claim they caused new clean power to be built. Other buyers have moved toward existing assets because they are easier to get. Wolf says prices for the two are now roughly comparable, so buyers of existing projects aren't getting a discount.
Outlook and what's left unsaid
Wolf expects prices for all PPAs to keep rising "for the foreseeable future." She points to geopolitical uncertainty and the coming expiration of federal renewable tax credits. The 2025 federal budget law cut short the wind and solar credits created by the Inflation Reduction Act. Projects now have to meet construction or in-service deadlines to qualify, which pushes developers and buyers to sign early. "It's still a matter of racing against the clock to lock in projects" that still qualify, she said.
The article leaves several questions open:
It doesn't split the Q3 increase between the tariff rush and costs already in equipment prices.
It doesn't explain how the $3–7/MWh tariff estimate was built.
It doesn't say whether prices might ease after the deadline-driven rush passes.
LevelTen's index is also built from offers on its own platform, not from signed deals across the whole market. And the 99% hyperscaler figure covers only Q1 new-build contracts.
Taken together, the numbers point one way. US wind and solar contracts have risen 13–28% in two years, and tariffs, permitting and expiring credits all add cost. Those costs land hardest on buyers who don't have a hyperscaler's purchasing power.
Remember
US wind contract prices are up 27.5% since 2024, about twice solar's 12.7% rise.
Hyperscalers signed 99% of new-build PPAs in Q1 2026; first-time buyers are at a low not seen since 2016.
Contracts with older projects are an alternative for smaller buyers, but they cost about the same as new-build ones.
The Nuclear Company (TNC), a startup founded in 2024 by former managers of Georgia's Plant Vogtle, has announced Prosperity One. It would put 6.6 gigawatts of large reactors on an undeveloped site along the Ohio River in Lewis County, Kentucky. The land was once assembled for a coal plant that was later abandoned. It sits half a mile from a 765-kilovolt power line into 1, the operator of the country's second-largest grid and arguably its most strained.
The site has room for six reactors, to be built two at a time. TNC is negotiating 2, long-term contracts with power buyers that help finance construction, and expects deals next year. It hasn't decided whether to run the plant itself or sell it to a utility.
The thesis
Much of the U.S. industry is chasing small modular reactors or new coolants. TNC wants to copy China's approach instead: pick one large, proven design and build it many times. The U.S. needed about 15 years to finish two Westinghouse 3, a 1.1-gigawatt reactor, at Vogtle. In the same period China built four, then turned the design into its own 4. China now runs 10 Hualong Ones and has at least 37 more coming.
The reason to repeat is the learning curve. Crews get faster, managers improve the build sequence, and suppliers see enough orders to expand factories and train workers. Vogtle Unit 4 (2024) came in roughly 30% cheaper and faster than Unit 3. Chief nuclear officer Joe Klecha calls that 30% "the floor" for savings between Prosperity One's first two units. That is a target, not a result.
TNC rules out mixing designs. It cites "Whoops": the Washington Public Power Supply System tried several reactor types at once, and its collapse in 1983 caused what was then the largest municipal bond default in U.S. history.
Which reactor
The AP1000 is the default. Last week the 5, the federal safety regulator, certified the Vogtle Unit 4 design as the settled blueprint. Klecha says TNC will look at other options until the site study ends in the first half of next year. South Korea's 6 is unlikely, given Westinghouse's 2022 lawsuit claiming it copied Westinghouse technology. GE's Advanced Boiling Water Reactor, which Japan built four times between 1996 and 2006, is the only other realistic choice.
Caveats
Most proposed AP1000s are at existing nuclear sites, so a new site is unusual. The article gives no cost estimate, schedule or financing plan. No contracts are signed, and the design isn't formally chosen.
The announcement
On Wednesday The Nuclear Company (TNC), a startup founded in 2024, announced Prosperity One. The plan is 6.6 gigawatts of large reactors on an undeveloped site along the Ohio River in Lewis County, Kentucky. The land was originally put together for a coal-fired power station that was later abandoned. It sits half a mile from a 765-kilovolt transmission line that connects to 1. PJM is the grid operator serving much of the mid-Atlantic and Midwest. It is the second-largest grid system in the country and arguably the most stressed, as data-center demand grows faster than new supply comes online.
The site has room for six reactors. Construction would go two at a time. TNC says it is negotiating 2, meaning long-term contracts with buyers to purchase the power, which would help finance construction. It expects to sign deals next year. It has not decided whether to run the plant itself as an independent power producer or sell it to a utility or another operator.
The thesis: copy what China did
Most efforts to revive U.S. nuclear have looked for a new design: smaller reactors, micro-reactors, or cooling with helium or molten salt instead of water. TNC's pitch is plainer. Use the large reactor America has already built, and build lots of them.
The comparison it is making is with China. The U.S. spent about 15 years finishing its first two 3 at Southern Company's Plant Vogtle in Georgia. In roughly the same period China built four AP1000s. It then reverse-engineered the technology into its own design, the 4, with a fully domestic supply chain. China now has 10 Hualong Ones operating and at least 37 more planned or under construction.
TNC was set up by hiring former Vogtle managers. One is Joe Klecha, its chief nuclear officer. "Our entire company was built for this purpose," he said.
How repetition is supposed to lower costs
The logic is a learning curve. With each identical unit, project managers find faster build sequences, workers get better at the specific tasks, and suppliers can justify spending on factories. Lin Yuan, senior advisor at the Nuclear Scaling Initiative, a nonprofit working on the commercial and policy conditions for scaling nuclear, said six AP1000s on one site "sends a strong signal to the supply chain." Manufacturers and skilled trades, she said, need to see "a sustained order pipeline to invest in capacity, factory expansion, and training."
Vogtle already shows the effect. Unit 4, which came online in 2024, cost roughly 30% less and was built roughly 30% faster than Unit 3, which finished a year earlier. Klecha calls that 30% "the floor" on savings between the first and second reactors at Prosperity One. He credits his team's experience and a "rigorous 'lessons learned' document." That figure is a company target. Nothing has been built yet.
Using one design is the central rule. TNC points to a well-known warning case nicknamed "Whoops." The Washington Public Power Supply System (WPPSS) tried to build several different reactor designs at once. The program collapsed, and in 1983 it caused what was then the largest municipal bond default in U.S. history. Mixing designs at Prosperity One "really goes against our mission," Klecha said.
Which reactor, really?
The AP1000 is the working assumption. Its position got stronger last week when the 5 (NRC), the federal nuclear safety regulator, certified the Vogtle Unit 4 design as the permanent, settled blueprint for future AP1000s. Klecha still left the door open: TNC will "evaluate other options" during 6, the geological and environmental study of the land, which he expects to finish in the first half of next year.
There are few realistic alternatives:
7. This is South Korea's large reactor, which is essentially derived from the American technology. Last month South Korea agreed to help the U.S. build up to six AP1000s at an undisclosed site, plus at least two APR1400s. For TNC it is unlikely. Westinghouse sued the Korea Electric Power Corporation in 2022, claiming the APR1400 copied its technology. The settlement lets Westinghouse demand royalties and keep the Koreans out of markets where it wants to compete.
Why a new site is unusual
Recent planning for new AP1000s has focused on sites that already host reactors or hold licenses. TNC's first major deal was to help Brookfield Asset Management, which owns 51% of Westinghouse, finish the abandoned AP1000 project at V.C. Summer in South Carolina. Other candidates mentioned include Florida Power & Light's Turkey Point, the Tennessee Valley Authority's Bellefonte site in Alabama, and two more units at Vogtle. Rampal says Prosperity One bucks that trend.
The policy backdrop is mixed. The Trump administration has pledged to finance at least 10 new large reactors. Yet the only U.S. projects that have actually broken ground are first-of-a-kind small modular reactors. Skeptics fear these will see Vogtle-style overruns while producing much less electricity to spread the costs over. Research covered last month suggests SMRs could face worse cost problems than large units.
What remains open
The article gives no cost estimate, schedule, financing structure or licensing timeline for Prosperity One. Offtake contracts aren't signed. The owner-operator model is undecided, and even the reactor design isn't formally locked in. A greenfield site, meaning one never developed for nuclear, will probably need more licensing and site work than adding reactors where they already exist. The article does not say how much more. Nor does it say whether the learning seen between Vogtle Units 3 and 4 will carry over to a different site with a different workforce.
Remember
The site is new for nuclear: a former coal site half a mile from a 765-kilovolt line into PJM.
TNC's cost case rests on Vogtle Unit 4 costing about 30% less than Unit 3.
Licensing disputes and past projects leave few realistic choices besides the AP1000 and GE's ABWR.
Wind turbines in New Mexico. PNM's proposal is built around an 800 MW wind farm in the state's east.
New Mexico is ahead of its own clean-energy law. The 2019 1 requires the state's investor-owned utilities to reach 50% renewable electricity by 2030, 80% by 2040 and 100% carbon-free by 2045. The state passed 50% renewable in 2024 and has kept climbing. Its largest utility, Public Service Company of New Mexico (2), got 80% of its electricity from carbon-free sources last year. That figure includes a small share of nuclear power imported from Arizona.
The state is doing this while demand rises. Consumption is expected to grow 40% by 2032. Dan West of the Clean Air Task Force, a climate nonprofit, says that unlike some of its neighbors, New Mexico has built "the institutions, the infrastructure… and the investment environment" to meet its targets, not just set them.
The easy part is ending
Early decarbonization is mostly a matter of adding wind and solar, which displace fuel-burning plants with cheaper electricity. New Mexico is dry, windy and has plenty of open land, which makes it well suited to that. The approach stops working once the grid has to meet demand in every hour, because wind and solar can't produce on command.
PNM's record peak demand is 2.3 gigawatts (GW), and it already has 5 GW of 3, meaning the plants' combined maximum output. Its planners model the hourly mix needed for every day of the next 20 years, including the rare "extra cloudy, totally still day." Other firm, clean sources don't help yet. Long-duration storage, advanced geothermal and green hydrogen are not bidding into PNM's competitive procurements. Laurie Williams, who leads PNM's planning, says they are "not economic," and some are years from being commercially available.
The proposal
In May, PNM asked regulators to approve roughly 1.7 GW of new resources:
800 MW of wind in eastern New Mexico
240 MW of solar
610 MW of batteries, split roughly evenly between four-hour and eight-hour systems
40 MW of gas, a 4 (a small plant that runs only at times of high demand) called La Luz II
The package would let PNM leave its 200 MW stake in the 5 coal plant in July 2031. Williams calls the gas unit the linchpin. "I can only meet the reliability and 6 metrics with the whole package," she said. Resource adequacy means having enough supply available in every hour.
The friction
Some environmental groups argue that building any new fossil plant before 2045 breaks the law's commitment to phase out fossil fuels. The state regulatory commission held hearings in October and will take up the gas plant specifically in January. Customers also worry that the pending takeover of PNM by 7, the world's largest private-equity firm, could change the utility's direction. The article also notes that bringing fossil-fuel workers through the transition has proved harder than building the clean plants.
New Mexico, a state better known for Hatch chiles and very old cultural centers than for grid policy, is ahead of schedule on clean electricity. The 2019 1 set binding targets for the state's investor-owned utilities: 50% renewable electricity by 2030, 80% by 2040 and 100% carbon-free by 2045. The state passed 50% renewable in 2024, six years early, and has kept going. Public Service Company of New Mexico (2), the largest utility, produced 80% carbon-free electricity last year. "Carbon-free" is a broader category than "renewable" because it counts nuclear, and PNM has a small allotment of nuclear power from Arizona.
Rep. Nathan Small, who sponsored the law, says beating the 2030 goal shows "we can actually move more quickly." Dan West, who covers Western state policy for the Clean Air Task Force, a climate nonprofit, argues that setting targets is "only half the job." In his view, New Mexico stands out among its neighbors because it also built "the institutions, the infrastructure… and the investment environment to deliver on them."
The state is doing this while demand climbs. Electricity consumption is expected to grow about 40% by 2032, so new clean generation is serving growth as well as replacing fossil plants.
Why the next stage is harder
The first half of decarbonization mostly comes down to adding wind and solar. Every kilowatt-hour they produce is one a gas or coal plant doesn't have to burn fuel for, and in a dry, windy state with wide open land, those kilowatt-hours are cheap. New Mexico is well placed for this phase.
The limit is that wind and solar produce when the weather allows, not when people need power. PNM's numbers show the gap. Its record peak demand is 2.3 GW, yet it already has 5 GW of 3 installed, meaning the combined maximum output of all its plants. That is more than twice the peak, and the utility still needs more. As an illustration (these are not PNM's figures): if much of that fleet is solar and wind, a hot evening after sunset with no wind leaves a large share of the 5 GW producing nothing, while air conditioners in Albuquerque still run.
Laurie Williams, PNM's senior vice president for integrated planning and transmission development, says the utility still needs "thermal resources," meaning fuel-burning plants, for that reason. Grids usually cover those hours with 4, meaning carbon-free sources that run on demand: long-duration storage, advanced geothermal, green hydrogen, or eventually fusion. According to Williams, none of these is bidding into PNM's competitive procurements, because they are "not economic," and some are years from commercial availability. Venture capital may be enthusiastic about them, but they are not yet available to buy at a competitive price.
How PNM chose its mix
Williams' team periodically runs a detailed statistical model of which combination of plants could meet demand in every hour of every day for the next 20 years. The model has to cover the stress cases, such as the "extra cloudy, totally still day" when wind and solar output collapses. The goal is 5, meaning enough available supply in every hour. Regulators measure it with reliability metrics.
The latest run produced the portfolio PNM filed with regulators in May, totaling roughly 1.7 GW:
The eight-hour batteries matter. A four-hour battery can shift midday solar into the early evening. An eight-hour unit can cover most of a night, which reduces how often anything else has to step in. The 40 MW La Luz II plant is a peaker, a small gas plant designed to run only during the tightest hours. It is less than 2.5% of the package. Williams calls it the linchpin. "The whole thing is interdependent, and I can only meet the reliability and resource adequacy metrics with the whole package," she said.
The package would also allow a coal exit. PNM holds a 200 MW stake in the 7 coal plant in northwestern New Mexico, which is operated by Arizona Public Service. The new resources could equip PNM to leave Four Corners in July 2031.
The objections
Some environmental groups oppose any new fossil-fuel plant before the 2045 deadline. They argue that building one conflicts with the law's legal commitment to phase out fossil fuels. The New Mexico regulatory commission held hearings in October and has more scheduled for January that focus specifically on the gas plant.
The disagreement is narrow but real. PNM's position is that 40 MW of rarely used gas makes 1,650 MW of wind, solar and storage reliable enough to approve, and lets 200 MW of coal close. Opponents question whether a new fossil asset belongs in a system legally bound to be carbon-free within two decades. The article does not say how many hours a year PNM expects La Luz II to run, what it would cost, or what alternatives, such as more batteries, the model rejected and why. Those are exactly the questions the January hearings would need to settle.
Other risks
Two other issues hang over PNM's plans. 8, the world's largest private-equity firm, is in the process of acquiring the utility. Customers worry that new ownership could change its direction on clean energy, and the article does not report any commitments Blackstone has made. The article also says New Mexico's experience shows that bringing fossil-fuel workers through the transition can be harder than building the clean plants. It does not give details on that point.
What to watch
New Mexico shows that a sunny, windy state with binding targets can move quickly through the cheap-renewables phase. Its next steps show what comes after. Without economic firm clean power, a utility at 80% carbon-free is turning to multi-hour batteries plus a small amount of gas to cover the worst hours. Whether regulators accept that, and whether firm clean technologies become cheap enough to replace it, will decide how New Mexico gets from roughly 80% to 100% carbon-free.
Remember
Having 5 GW of capacity against a 2.3 GW peak still isn't enough when most of it depends on the weather.
PNM says firm clean options like geothermal and long-duration storage aren't bidding because they aren't yet economic.
Eight-hour batteries make up about half the proposed storage, aimed at covering whole nights rather than just evening peaks.
A company running cloud and AI data centers at huge scale, such as Google, Microsoft or Amazon.
Image: Latitude Media
Google and Entergy Arkansas have amended their deal to power Google's data center in West Memphis, Arkansas. The new terms let the campus use more power, sooner. They also respond to a months-long backlash after ordinary customers were billed for a solar plant that Google's payments more than cover.
The original deal
The 2025 contract included Cypress Solar, a $1.6 billion solar-and-battery project. Google committed $443 million up front plus at least $83 million a year for 20 years, about $2.1 billion in total. Even so, Entergy's other customers saw a new charge on their bills this summer, partly to pay for building the plant.
Why customers paid
It comes down to accounting. The 1, a 2025 state law, lets utilities bill customers for financing a plant while it is still under construction, through a separate bill line called the "2." Entergy plans to collect about $33 million this way in 2026.
Entergy treated Google's money as ordinary revenue, not as a contribution toward building the plant. Counted as a contribution, it would have cut the plant's booked cost. That cost is the base on which a regulated utility earns its return. Counted as revenue, the plant stays at full cost, and Google's payments lower everyone's rates gradually over time. Customers pay now and get relief later.
Critics say Entergy wanted the larger return. Entergy argues that netting the money against the plant would also have cut Google's monthly bills, so the data center would do less to hold down other customers' rates.
What changes
When Cypress Solar starts running in late 2028, it moves from the rider into 3 (normal rate-case pricing). There, its costs and Google's payments offset each other. The construction charges customers are paying now remain.
The expansion adds 1,400 4 of batteries (about $550 million), a bigger substation, two transmission lines, and a 440-megawatt solar purchase deal from the Big Island Project.
Still a black box
The figures came out only because the Arkansas Democrat-Gazette published numbers from the sealed contract in August. Entergy then sued the paper. The new agreement was also filed under seal. Nick Zenkin of Latitude Intelligence, the research arm of the publisher, Latitude Media, called it "a step in the right direction" but less transparent than a published 5.
Zenkin says it's common for a utility to build the plants while the customer signs a long contract. What's unusual in Arkansas is booking a large prepayment as revenue to credit back later while other customers finance construction. Georgia, Mississippi, Missouri and South Carolina have laws like Arkansas's.
The news
Google and Entergy Arkansas have amended the contract that supplies power to Google's data center in West Memphis, on the Arkansas–Tennessee border. The new terms let the campus draw more power and ramp up faster. The change also tries to settle a months-long dispute over how Entergy is paying to build the solar plant that serves the campus. The dispute began because ordinary Entergy customers saw a new construction charge on their bills, even though Google's payments under the contract add up to more than the plant costs.
The original deal
The 2025 agreement included Cypress Solar, a $1.6 billion solar-plus-battery project. Google committed to:
$443 million in accelerated (up-front) payments, and
a minimum of $83 million a year for the contract's 20 years, which comes to roughly $1.66 billion.
Total payments come to about $2.1 billion, more than the plant's estimated construction cost. Even so, Entergy's existing customers got a new monthly charge over the summer, partly to fund Cypress Solar.
Why customers were charged
The answer is an accounting choice. Arkansas's 2025 1 lets utilities bill customers for the financing costs of projects that are still under construction. These costs show up on bills as the "2," a separate line item. Entergy put Cypress Solar through this route and plans to collect about $33 million from existing customers in 2026.
Entergy then treated all of Google's money, both the $443 million prepayment and its monthly bills, as ordinary utility revenue. It did not count the money as a contribution toward building the plant. That choice matters:
As a construction contribution, Google's money would directly reduce Cypress Solar's booked cost. A smaller 3 means a smaller return for Entergy, and a smaller amount for other customers to finance.
As revenue, the plant stays on the books at full cost, and Entergy earns a return on all of it. Google's payments go toward total system costs and lower everyone's rates over time.
Here is an illustration with round numbers, not drawn from the filings. Suppose a utility's allowed return works out to 10% a year. If a $443 million prepayment is subtracted from a $1.6 billion plant, the utility earns on about $1.16 billion. If the prepayment is booked as revenue instead, the utility earns on the full $1.6 billion, and customers get the $443 million back gradually as credits. Under the second approach, customers pay financing charges now and receive the benefit later.
Entergy says Google's revenue will eventually lower other customers' bills. Critics, including local news outlets and industry stakeholders, argued that the setup makes existing customers pay first and wait for relief.
Entergy's defense
Critics say Entergy picked the revenue treatment because netting Google's money against the plant would have cut the return it earns. Entergy gives a different reason. Reducing the plant's booked cost would also have lowered Google's negotiated monthly bills, it argues, which would weaken the large load's long-term effect of holding down everyone else's rates. In this week's filings with the Arkansas Public Service Commission, Entergy said it wanted to "correct the misinformation and inaccurate reporting" about whether Google really pays for Cypress Solar.
What the amendment changes
Cypress Solar's accounting. When the plant starts operating in late 2028, it will leave the GAJA rider, and its costs will be recovered through 4, the normal rate-case process. That puts the plant's costs and all of Google's payments in the same regulatory bucket, where they offset each other. It does not remove the construction charges customers are paying now.
A bigger, faster campus. The amendment raises the campus's maximum demand and lets Google reach it sooner. Supporting this are:
two battery projects totaling 1,400 5 of storage, estimated at about $550 million,
an expanded substation near the site,
two new transmission lines, and
a separate 440 MW solar 6 (a long-term contract to buy a plant's output) with the Big Island Project.
No more GAJA rider for these projects. None of the new projects will use the rider. Google will pay the batteries' construction financing through scheduled payments. Once the batteries are running, their ongoing costs go into regular rate setting and are offset by higher fixed monthly charges on Google's bill. Entergy says it will pass the benefit to other customers as lower rates starting in 2032.
How common this is
Nick Zenkin, director of research at Latitude Intelligence (the research arm of the publisher, Latitude Media), says much of the structure is now standard. The utility builds and owns the plants. The customer signs a long contract and pays for its own transmission. Up-front payments often cover transmission, and minimum bills cover generation over time.
Two features stand out in Arkansas. Google's large prepayment is counted as rate revenue to be credited back later, while other customers pay construction financing through a rider in the meantime. And the contract is mostly sealed. Arkansas has no 7 (a standard, published rate schedule) specifically for data centers. Many utilities elsewhere are moving large loads onto such tariffs, which are more transparent. Instead, each large customer signs a custom contract, and plants built partly for them can be charged to all customers during construction. Georgia, Mississippi, Missouri and South Carolina have similar laws.
Transparency
The public learned the payment figures only because the Arkansas Democrat-Gazette published numbers from the sealed contract in late August. Entergy responded by suing the paper in federal court. The amendment doesn't open things up. Entergy asked regulators to waive earlier calls for more disclosure and filed the new agreement under seal, including how Google's rates were set. Zenkin called it "a step in the right direction," but said it "isn't as transparent as a tariff because most of the terms are still hidden."
What's still unclear
The article doesn't say how large Google's new demand ceiling is or how fast the ramp-up will be. It doesn't give Entergy's allowed return, or how much existing customers will pay in total under the GAJA rider before Cypress Solar moves to base rates in 2028. With the contract sealed, outsiders can't check Entergy's claim that the revenue treatment leaves other customers better off in the long run.
Remember
Whether a large customer's prepayment counts as revenue or as a construction contribution decides who pays first and how much the utility earns.
Laws in Arkansas, Georgia, Mississippi, Missouri and South Carolina let utilities charge all customers for plants while they are still being built.
Custom contracts filed under seal mean the public can't check claims that data centers lower other customers' bills.
8. This is General Electric's Advanced Boiling Water Reactor, described as the world's first so-called advanced reactor. Boiling water reactors make up about a third of the U.S. fleet and are the second most common type after Westinghouse's pressurized water design. Japan built four ABWRs between 1996 and 2006. Taiwan nearly finished two before cancelling them as part of phasing out nuclear power. The NRC has certified the ABWR, but a South Texas project to build the first U.S. units was scrapped about a decade ago. Consultant Brett Rampal, who advises Deloitte and Veriten, praises its construction record but still sees the AP1000 as the front-runner.
Resource
Size
Wind, eastern New Mexico
800 MW
Solar
240 MW
Batteries (about half 4-hour, half 8-hour)
610 MW
Gas 6, La Luz II
40 MW
None of these projects will use the GAJA rider. Google pays the batteries' construction financing directly. Entergy says the benefit will reach other customers as lower rates from 2032.