Pitch Prices, Shopping Bots and Smoke Signals · Morning Gist
Sunday, October 115 stories · 16 min
Pitch Prices, Shopping Bots and Smoke Signals
Private equity buys into football, AI agents may stop firms profiting from our inattention, and one stock-market pattern turns out to be statistical noise.
Picked from 37 new articles across 16 sources · arrow keys for other days
Today in 30 seconds
30s left
Liverpool's value went from £300 million to £5.5 billion, and a fifth of England's 92 professional clubs now have private-capital owners. story 1 ↓
AI shopping agents could hurt businesses that rely on customer inattention, Collison argues. Cowen warns agents could also help sellers collude. story 2 ↓
A study linking UK No Smoking Day to lower stock returns only held up after adding controls. Klement calls it data mining. story 3 ↓
In a survey of 4,314 Japanese adults aged 55 to 75, most would pay about 8% more for robot-assisted nursing homes. story 4 ↓
A retiree near 80 split a $100,000 test portfolio 30/30/40. It has paid 3.8% a year for 30 months and still grown. story 5 ↓
Nearly four in ten laid-off workers use up their unemployment benefits before finding work, so the job market is cooler than headlines suggest.
1/5Net Interest· Marc Rubinstein· Oct 10
Liverpool FC's value rose from £300 million to £5.5 billion, and private equity is buying in
Marc Rubinstein uses the single Liverpool FC share he once owned to trace how club values grew so large that only big investment funds can now afford them. He also asks whether football can make investors money.
Why it matters · Private equity firms are pitching sports as a new asset class. Football club valuations show how these firms find returns, and how far prices have outrun the wealth of local owners.
Know this first
Context from the editor, not the article · 32 sec
1 · How English football is organised
England has 92 professional clubs. The top 20 play in the Premier League. Below them, the English Football League (EFL) runs three divisions: the Championship, League One and League Two. Most of the money, mainly from TV rights, flows to the Premier League.
2 · What private equity does
Private equity firms raise money from pension funds, endowments and other institutions. They buy stakes in businesses, try to make them more valuable, then sell within years. They are judged on annual return and on how many times the money invested comes back.
3 · Who used to own clubs
2/5Marginal Revolution· Tyler Cowen· Oct 11
How AI shopping agents could shift power from companies to consumers
Patrick Collison, CEO of the payments company Stripe, argues that AI agents shopping for consumers will undercut upsells, coupons and paid placement, and reward better products. Economist Tyler Cowen warns they may also enable price collusion.
Why it matters · Many profitable business models depend on customer inattention: forgotten subscriptions, overpriced add-ons, paid search placement. Agents that pay attention for you would change who profits.
Know this first
Context from the editor, not the article · 24 sec
1 · What personal agents are
AI agents are software built on large language models that act for a user: searching, comparing and buying things. The essay imagines everyone having one that handles purchases and subscriptions.
2 · Bounded rationality
Economist Herbert Simon's idea that people have limited time, attention and information, so they settle for good-enough choices. Firms with dedicated analysts can design prices and checkout flows to exploit those limits.
3 · Price discrimination
Charging different customers different prices for the same thing. Coupons are a classic example: price-sensitive shoppers take the trouble to find them, while less careful buyers pay full price.
3/5Klement on Investing· Joachim Klement· Oct 2
Study links UK No Smoking Day to lower stock returns; Klement calls it data mining
A Greek economist reports that Britain's FTSE 100 index does worse on the annual No Smoking Day. Investment writer Joachim Klement argues the result is weak and only passes statistical tests after questionable tweaks.
Why it matters · Many "market anomalies" sold as strategies are built this way, and spotting the warning signs keeps you from paying for patterns that were never really there.
Know this first
Context from the editor, not the article · 27 sec
1 · What a market anomaly is
An anomaly is a return pattern that standard theory says shouldn't persist, like calendar effects (e.g. the 'January effect'). Researchers hunt for new ones because a novel anomaly is publishable and might, in theory, be exploitable.
2 · Statistical significance levels
A result "significant at the 5% level" would show up by pure chance less than 5% of the time if no real effect existed. Journals generally want 5%; 10% is a weaker, less convincing threshold.
3 · Why data mining fools people
Test enough variables, time periods or model specifications and some will look significant by luck. Reporting only the version that clears the bar makes noise look like a discovery. This is also called p-hacking.
4/5Marginal Revolution· Tyler Cowen· Oct 4
Survey finds most older Japanese prefer nursing homes that use robots
Economists asked 4,314 Japanese adults aged 55 to 75 to pick between two nursing homes. 65% chose the one that uses robots for part of the care. On average they would pay 8% more for it.
Why it matters · Paying for elder care is a growing cost for families and governments. If people accept and will pay for automation, it could ease caregiver shortages without cutting the care itself.
Know this first
Context from the editor, not the article · 26 sec
1 · Japan's care worker gap
Japan has one of the world's oldest populations. Demand for long-term care is rising faster than the supply of care workers, so Japan has been testing caregiving robots and digital monitoring in nursing homes.
2 · Willingness to pay
Willingness to pay, or WTP, is the most extra money a person says they would spend to get one option over another. Economists use it to put a value on things that markets don't price cleanly.
3 · Stated vs revealed preference
Surveys capture stated preferences: what people say they would choose. Revealed preferences come from real purchases. Stated answers can drift from actual behaviour, especially for choices people haven't faced yet.
5/5HumbleDollar· Gordy Vytlacil· Oct 4
A retiree near 80 tests living on portfolio income alone
A retiree entering his 80s is running a three-year test: spend only a three-fund portfolio's dividends and interest, and reinvest everything else. So far it has paid 3.8% a year and grown 11% a year.
Why it matters · Planning for a time when you can no longer manage your own money is a real retirement problem. This is a concrete, measured attempt to reduce how many decisions a portfolio needs.
Know this first
Context from the editor, not the article · 31 sec
1 · Total return versus income
Total-return investors count price gains plus dividends and sell shares when they need cash. Income investors spend only the dividends and interest. Before taxes and costs, the two give the same result. The difference is in how many decisions you have to make and how you feel about selling.
2 · Required minimum distributions
Required minimum distributions (RMDs) are yearly withdrawals the IRS requires from traditional IRAs and 401(k)s once you reach your 70s. The required share grows with age. Roth IRAs have no RMDs for the original owner.
3 · The 60/40 portfolio
"60/40" means 60% stocks and 40% bonds. Stocks usually rise faster than bonds, so over time the mix drifts toward more stock. Rebalancing means selling some of the winner to get back to the target mix.
For decades, English clubs belonged to local businessmen who supported them. Then came foreign billionaires such as Roman Abramovich, who bought Chelsea in 2003. Later came state-linked funds, such as the Abu Dhabi group that owns Manchester City.
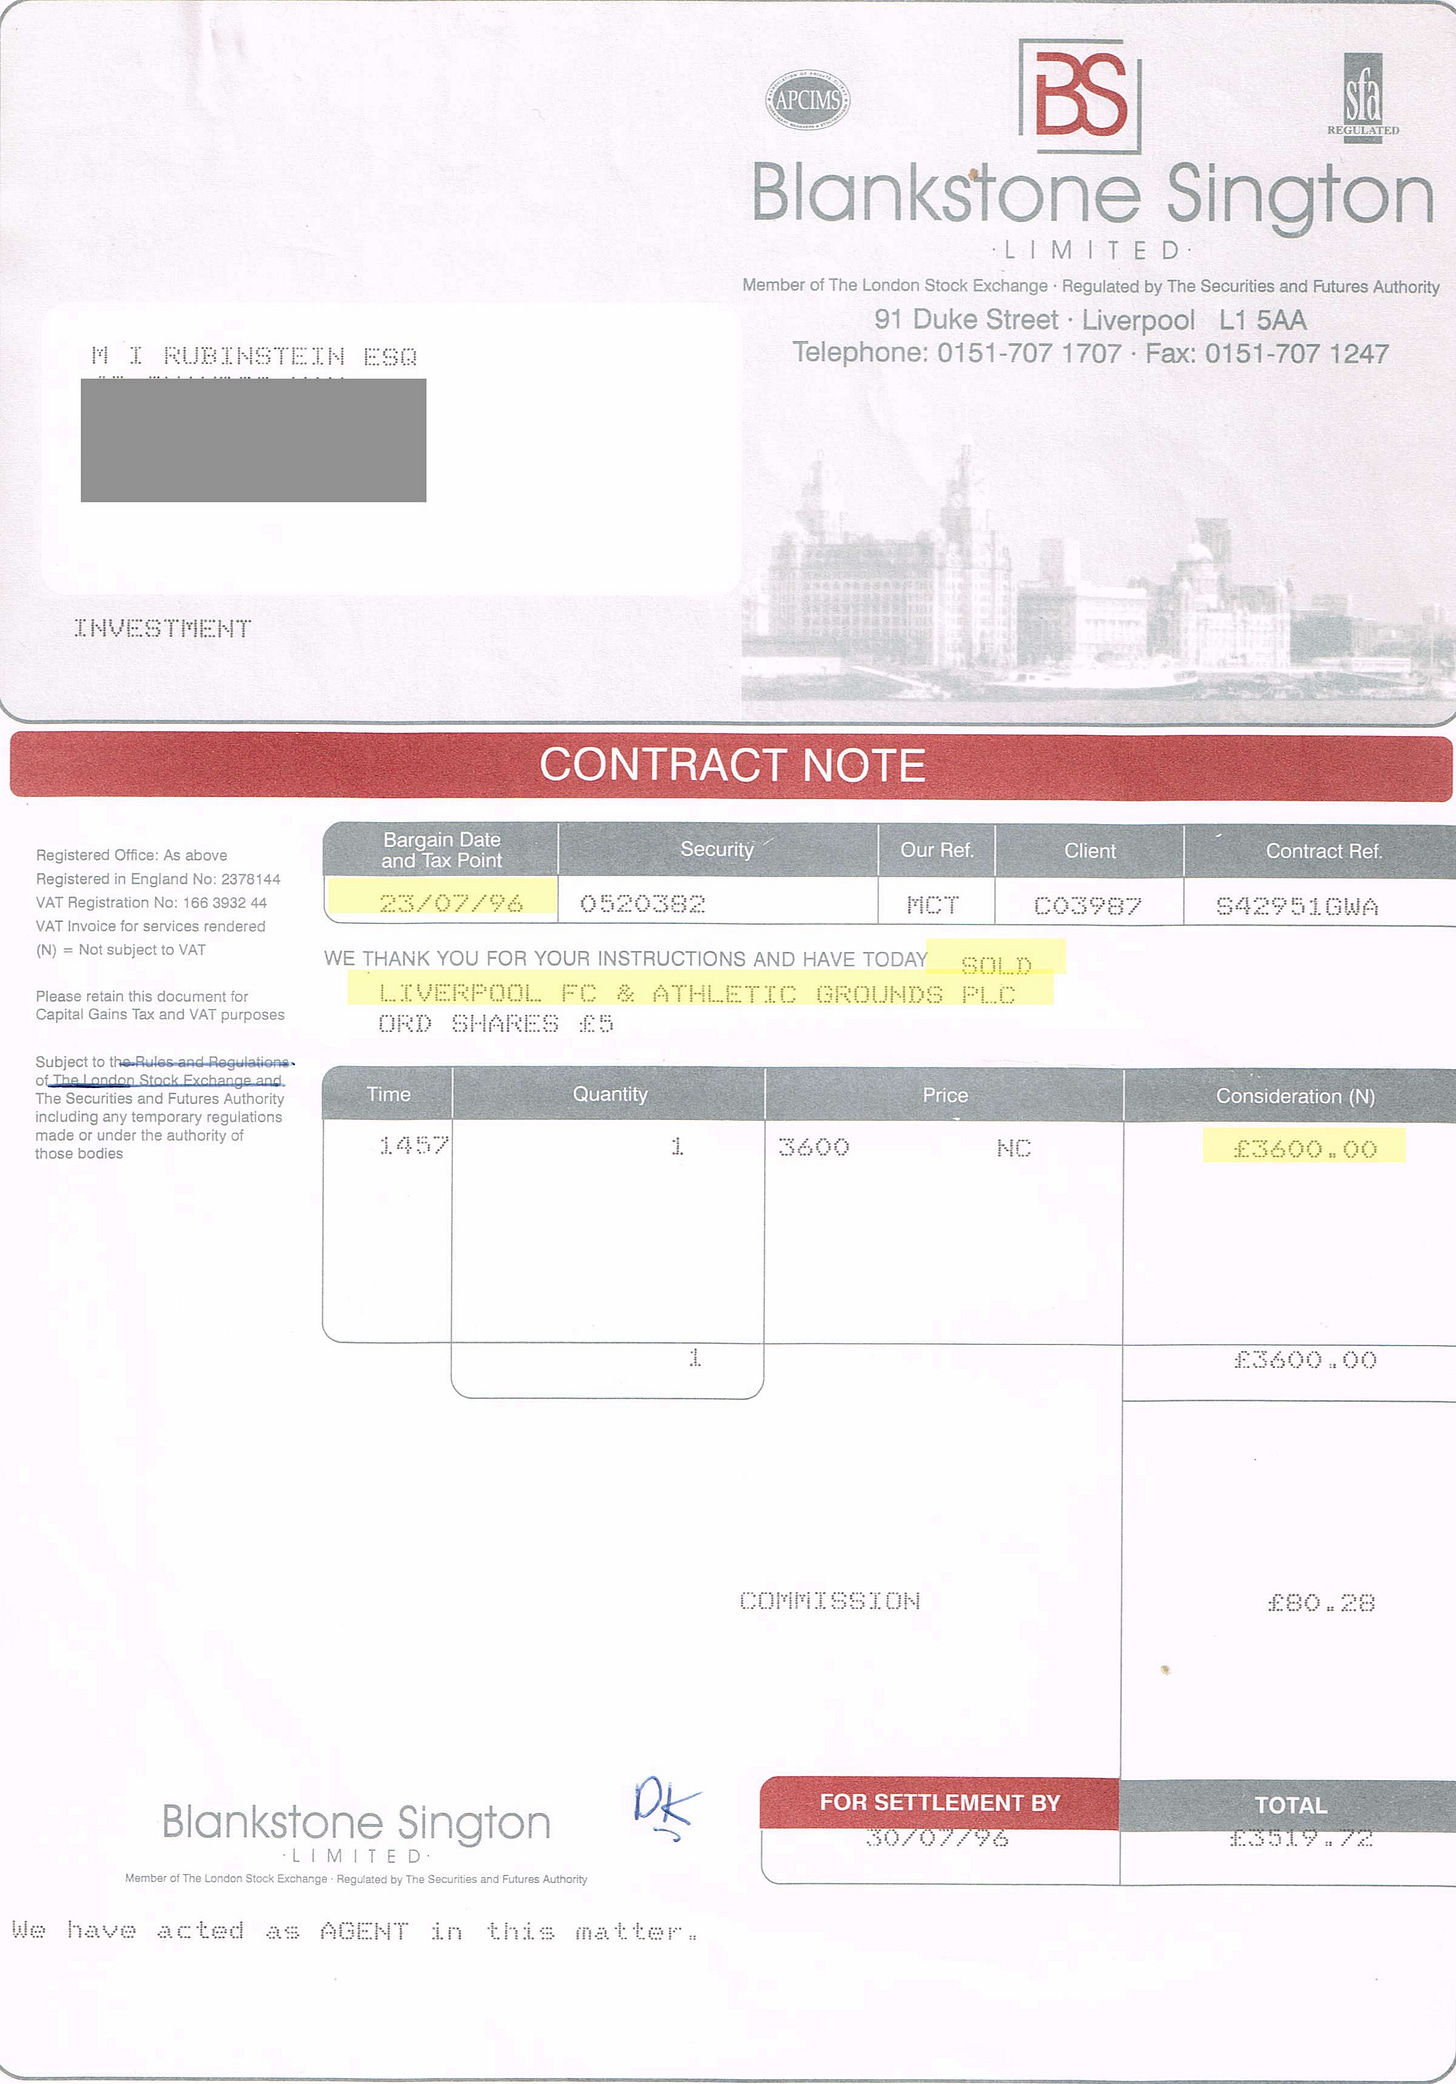
"The one that got away": the author's Liverpool FC share, sold in 1996 after doubling in value.1 / 2
Marc Rubinstein, who writes the Net Interest newsletter, once owned one share in Liverpool Football Club. He uses that share to explain a shift in who can afford to own an English football club. The answer, more and more, is institutional 1.
One share, 1996
The Moores family, heirs to the Littlewoods retail and betting fortune, held a majority of Liverpool. A small minority of shares had passed among fans since 1892. From 1991 they could be traded 2 on a broker's platform. That means buyers and sellers were matched directly instead of on a stock exchange. In 1996 Rubinstein paid £1,950 for one share, plus 2.2% commission.
That summer England hosted the 3 tournament, football became fashionable, and the share doubled in value within months. He sold. Afterwards the shares traded below his sale price for more than a decade. They only went higher in 2007, when Americans Tom Hicks and George Gillett bought the club at £5,000 a share. To get the last small holders to sell, the buyers gave them lifetime priority on tickets for cup matches. Rubinstein regrets missing that perk more than the price rise.
From £125 million to £5.5 billion
1996: equity value £125 million
2007: £174 million, or £219 million counting £45 million of debt
2010:4, owner of the Boston Red Sox, bought the club at £300 million
August 2026: a consortium called 1892 Holdings bought 38% at a value of about £5.5 billion ($7.3 billion)
That is roughly 18 times FSG's entry price. Over 16 years it works out to about 20% a year, by our rough calculation.
Too expensive for billionaires
In 2010, every member of the 5 list of richest Americans could have bought Liverpool for less than half their net worth. Today only 88 could. Wealth funds owned by governments could fill the gap. But stricter regulation and the dispute over Abu Dhabi's ownership of Manchester City make that less likely, Rubinstein argues.
Private equity is moving in instead. A fifth of England's 92 professional clubs now have private capital among their owners, up from 8% in 2010. In the Premier League the figure is 40%. Clearlake Capital took full control of Chelsea last month at a £5 billion valuation. KKR bought Arctos Partners, a sports investor, and Apollo launched Apollo Sports Capital. Apollo puts the whole sports market at $2.5 trillion. KKR sizes the market it can target at $650 billion and estimates that private capital owns only about 2% of it.
The open question
Former owner David Moores said that if he had run Liverpool as an "investment", "we'd have come unstuck pretty quickly." Rubinstein asks whether that has changed. His answer is behind the newsletter's paywall and is not in the text available here.
Marc Rubinstein writes Net Interest, a newsletter about finance. He opens this piece with a confession: for a few months in 1996 he owned part of Liverpool Football Club. One share. He uses it to follow the club's value over 30 years. That story shows why 1, rather than local businessmen or even oligarchs, is becoming the main buyer of English football clubs.
How a fan could buy a share
In 1996 the Moores family, heirs to the Littlewoods retail and football-betting fortune, controlled Liverpool. Chairman David Moores held 51%. A small minority of shares had been held by fans and individual investors since the club was founded in 1892. For about a century those shares mostly passed down through families. When they did change hands, it was through private negotiation.
That changed in 1991. A London broker started a platform to trade unlisted shares "2" under Stock Exchange rules. Over the counter means a broker matches buyers and sellers directly instead of listing the shares on an exchange. Liverpool FC and Athletic Grounds PLC became one of its best-known names. Rubinstein left a buy order with his broker, was eventually matched with a seller, and paid £1,950 plus 2.2% commission for a single share.
Good timing, then a decade of nothing
England hosted the 3 European Championship that summer. "Pre Euro 96, football was incredibly unfashionable," Moores later said. After the tournament the country went football mad, and within a few months Rubinstein's share had doubled. He had just bought his first home and needed the money, so he sold.
Measured by price, the sale was well timed. For more than a decade afterwards, the shares traded below what he got for his. They went higher only in 2007, when Americans Tom Hicks and George Gillett bought the club at £5,000 a share. His regret was something else. To persuade the remaining small shareholders to sell, the buyers offered lifetime priority to buy tickets for home cup matches and cup finals. Liverpool has played in nine cup finals in the past ten years, so that perk turned out to be valuable.
The valuation path
Rubinstein tracks the club's equity value, meaning the value of the shares not counting debt:
He compares FSG's result with his own using two common return measures. The first is 5 (internal rate of return), the annualised return, which favours fast gains. The second is the 6, how many times the money comes back. Doubling his money in a few months gave him an enormous annualised figure. FSG's 18-fold rise in value over 16 years gives the larger multiple. As a rough check of our own: 18 times over 16 years is about 20% a year compounded. That figure ignores any extra money FSG put in, which the article does not discuss.
Priced out
As values climbed, the local supporter-owner disappeared. "With the influx of more and more overseas superstars on superstar wages, I was aware the game was changing beyond all recognition," Moores said. "The Abramovich era was upon us, and I knew that I could never compete." Roman Abramovich, the Russian billionaire, bought Chelsea in 2003.
Now even very rich individuals struggle. Rubinstein's measure: in 2010, every member of the 7, the list of the richest Americans, could have bought Liverpool for less than half their net worth. Today only 88 can, even though global wealth has grown a great deal since then.
8, which invest money for governments, have filled part of the gap. Rubinstein argues that tighter regulation and the continuing controversy over Abu Dhabi's ownership of Manchester City make more of these deals less likely.
Private equity moves in
The newer source of money is institutional private equity. These firms pool money from pension funds and other institutions to buy stakes in businesses, and aim to sell later at a profit. Figures from the International Centre for Sports Studies show that a fifth of England's 92 professional clubs now have private capital in their ownership, up from 8% in 2010. The 92 are the Premier League plus the three divisions of the English Football League (EFL): the Championship, League One and League Two. In the Premier League alone the share is 40%.
Firms are building teams to do these deals:
KKR bought Arctos Partners, a sports investor, this year to give itself a foothold in sports.
Apollo set up Apollo Sports Capital as a separate business.
Sixth Street, TPG and Avenue have all raised money for sports investing over the past year.
Clearlake Capital took full control of Chelsea last month at a £5 billion ($6.7 billion) valuation.
Silver Lake, an investor in Manchester City, is watching closely.
The firms describe the opportunity in big numbers. Apollo's Al Tylis calls sports a new asset class. He estimates it at $2.5 trillion across leagues, venues, media, merchandise, fitness and live events. KKR uses a narrower figure of $650 billion that it can realistically target. Both say the sector is short of capital, and KKR estimates private capital owns only about 2% of it. These are the firms' own estimates, and both firms are trying to raise money for the strategy.
What's left open
The key question is whether football makes money for investors. Moores was blunt about his years in charge: "If we'd have done it as an 'investment' we'd have come unstuck pretty quickly." Rubinstein promises to examine the economics of football and what private equity sees in it, but that analysis sits behind the newsletter's paywall. The text available here therefore shows the rise in valuations and the change in who buys clubs. It does not show whether clubs earn enough cash to justify those prices, or whether investors are counting on the next buyer paying even more.
Remember
Liverpool's value barely grew from 1996 to 2007, then rose about 18 times under FSG between 2010 and 2026.
Only 88 of the Forbes 400 could now buy Liverpool for half their wealth, versus all 400 in 2010.
Private capital sits in 40% of Premier League clubs, and KKR, Apollo and Clearlake are building sports businesses.
Economist Tyler Cowen has posted notes from Patrick Collison, CEO of the payments company 1, on his blog Marginal Revolution. The notes ask what happens to markets when AI agents, software that researches and buys on our behalf, do our shopping. It is speculation about mechanisms rather than data, but the mechanisms are concrete.
Firms win on attention
Collison calls companies "the original superintelligence." A firm can spread the cost of analysts and pricing experiments across millions of customers, while each customer is short on time and information. Economist Herbert Simon called this 2, and firms profit from it. Collison's example is the travel-insurance upsell at checkout, which he says is often priced well above an ordinary policy. An agent that reads every option would close much of that gap.
What changes
He leaves two questions open. Will agents send everyone to the same winning product, or spread purchases across individual tastes? And will agents actually work for consumers? Everything above assumes they do. An agent that takes merchant referral fees would bring back the bias it was meant to remove.
Cowen's warning
Cowen adds a counterweight. Sellers will run agents too, and those agents may collude to hold prices up. Regulators could struggle to stop this because it is "illegible": hard to see or prove, and possibly not even intended by the merchants. Collusion tends to fall apart, though. So Cowen expects some prices to drift up and then drop suddenly when the arrangement breaks down or a new competitor enters.
The upshot
Buyer agents push margins down and reward better products. Seller agents may push prices up in unstable bursts. Neither author estimates how large either effect will be. The essay's main use is as a checklist of which profits depend on customers not paying attention.
Economist Tyler Cowen has published a set of notes from Patrick Collison, CEO of the payments company 1, on his blog Marginal Revolution. The notes ask what happens to markets when consumers hand their shopping to AI agents, software that searches, compares and buys for them. Cowen adds a warning of his own. Neither offers data. This is informed speculation about mechanisms, and it is worth reading that way.
Companies as the original superintelligence
Collison opens with a provocation: companies are "in some sense the original superintelligence." A firm can spread the cost of thinking over millions of customers. He calls this its "amortized cognitive surplus." It can pay analysts to tune every price and every checkout screen. Each customer, by contrast, is often inattentive, underinformed or irrational.
He ties this to Herbert Simon's idea of 2: people have limited time and attention, so they settle for choices that are good enough. Firms often profit from that gap. His example is the travel-insurance upsell at the end of a booking, which he says is typically priced well above what a regular policy would cost. A personal agent that never tires and reads every option would narrow the gap. Collison expects consumers to become "somewhat more rational" in their dealings with companies.
What breaks: discrimination and cross-subsidies
Two familiar business practices depend on uneven attention.
Price discrimination, meaning charging different people different prices for the same thing. Coupons work because only some shoppers bother to hunt for them. If every agent hunts "fastidiously," the coupon stops sorting customers.
3 between customers. Collison notes that people who forget to cancel subscriptions subsidize those who remember. An agent that remembers removes that pool of revenue, and prices may need to rise for everyone else.
A simple illustration (these numbers are not from the article): a streaming service charges $10 a month. A fifth of its subscribers stopped watching but never cancelled. If agents cancel those accounts, the service loses that revenue. It might raise the price for active users, so the attentive, who used to get a quiet discount, now pay more. Collison admits he doesn't know the "4," economists' term for who ultimately bears a cost or gain, across the whole economy.
A subsidy for quality
Collison sees the biggest effect here. Corporate strategy has long argued over distribution versus product quality: a better mousetrap doesn't help you if everyone keeps buying ACME's because it's what they know. He asks how markets would look "if individuals always spent at least 10 hours researching their purchases." Agents would make something like that free. He argues they would act as a "structural subsidy for product quality," so that improving the product becomes a more effective strategy than winning shelf space or attention.
A corollary: information about quality becomes more valuable. Today most people can't gather and combine reviews, test results and reliability data. Agents will have an "insatiable thirst" for such signals. Collison points out that this makes data valuable for a second reason. The usual reason is that data trains AI models. The second is that data complements intelligence that has become cheap.
He describes the market as a "massively parallelized, decentralized, and highly imperfect value attribution machine." It is a system that works out which products deserve reward. He borrows "5," the method neural networks use to send error signals back so they can adjust, as a metaphor. In his view, agents would strengthen the signal that rewards better products. He calls this possibly "too optimistic."
Open questions he raises
Superstars or dispersion? If rational agents all reach the same conclusion, sales could pile onto one winning product, a "6." Or agents could draw out each person's actual tastes and spread purchases more widely, undoing what Collison calls the "artificial clustering" that mass marketing produces.
Cowen's addition: algorithmic collusion
Cowen expects one more effect: more volatile prices. Sellers will use their own agents to set prices, and those agents may end up colluding, effectively coordinating to keep prices high. This could be "illegible," meaning hard for regulators to see or prove, and even unintended by the merchants themselves. Antitrust law is built around explicit agreements, so it may have no simple tool against it. But collusion tends to be unstable. Cowen's picture is prices that drift up for a while, then drop suddenly when the arrangement breaks down or a new competitor enters.
How to weigh it
The two effects pull in different directions. Buyer-side agents push toward lower margins on add-ons, fewer forgotten subscriptions and more reward for quality. Seller-side agents may push prices up through tacit coordination. Neither author offers evidence on how big either effect would be, or how fast agents will be adopted. The essay is most useful as a checklist of which profit sources depend on customer inattention, and so which ones capable agents could threaten.
Remember
Coupons, forgotten subscriptions and checkout upsells all depend on customer inattention, and agents remove it.
Collison argues agents would reward product quality over distribution, making reliable quality data more valuable.
Cowen warns that seller-side pricing agents could collude in ways hard to detect, making prices rise and then crash.
The paper's chart: average FTSE 100 returns on No Smoking Wednesdays versus other Wednesdays.
Joachim Klement, who uses his Friday posts to poke at weird economics research, has taken aim at a 2026 paper by Evangelos Vasileiou of the Hellenic Mediterranean University in Greece. The paper claims that UK stocks do worse on No Smoking Day.
The claim
No Smoking Day is a UK campaign that asks smokers to give up cigarettes for one Wednesday each year. Klement, who has lived in the UK for ten years, says he had never heard of it. Vasileiou was looking for a new 1, meaning a return pattern standard theory can't explain, driven by psychological stress. He compared returns on the 2, the index of the 100 largest companies listed in London, on No Smoking Wednesdays with returns on all other Wednesdays.
No Smoking Wednesdays came out lower. The implied story is that investors in nicotine withdrawal take less risk.
Why Klement isn't convinced
The evidence is weak. The gap was only statistically significant at the 10% level. That is a looser bar than the 5% level journals usually expect. A 10% threshold means a gap this large would turn up by chance about one time in ten even if there were no real effect.
The time period was cut up. A 3, a test that looks for the date when a pattern changes, picked out 1991. Before then there was no difference. After 1991 there was one, but it was still significant only at 10%.
The controls did the work. The result only reached 5% once Vasileiou added three 4, extra factors included to account for other influences:
the share of UK adults who smoke
the share of smokers who quit
the share of people who own shares directly
Klement points out that the first two are closely tied to each other, because the smoking rate falls mainly when people quit. Putting two such overlapping variables in the same model, he argues, "invalidates the entire statistical approach." He sees no reason why direct share ownership should matter at all. All three variables are basically smooth trends over time, two falling and one rising. Adding trends like these can shift a test result without saying anything about smoking or stress.
The verdict
Klement's word for it is 5: trying periods and variables until the result crosses the 5% line that makes a paper publishable. The paper's own chart of average returns shows the gap. The question is whether anything real sits behind it.
For investors, this is a familiar warning sign. Be wary of a calendar effect that only shows up after the time period has been chopped up and the model filled with unrelated trends.
Joachim Klement uses his Friday posts for the odd corners of economics research, including studies he thinks should never have been posted. His latest target is a 2026 paper by Evangelos Vasileiou of the Hellenic Mediterranean University in Greece. It argues that the UK stock market does worse on No Smoking Day.
The hypothesis
Researchers put a lot of effort into finding market anomalies: return patterns that standard finance theory says shouldn't persist. Well-known examples include calendar effects such as the "January effect" and the idea that weather or sports results move share prices. A new anomaly is publishable, and in principle it might be tradable. Vasileiou set out to find one driven by psychological stress that nobody had described before.
His candidate was No Smoking Day, a UK campaign that asks smokers to stop for one Wednesday a year. Klement is sceptical that the day affects anyone's behaviour. He has lived in the UK for ten years and says he first heard of it through this paper. He also notes that the campaign's website still advertises the March 12, 2025 event, although the next one is on March 10, 2027.
The test is simple. Take the 1, the index of the 100 largest companies listed on the London Stock Exchange. Compare its returns on each year's No Smoking Wednesday with its returns on every other Wednesday. Using only Wednesdays removes any day-of-the-week effect. The paper finds lower returns on No Smoking Wednesdays. The implied explanation is that investors going without nicotine become more risk-averse.
First problem: the result is weak
The difference was statistically significant only at the 10% level. Put simply, if No Smoking Day had no effect at all, a gap this large would still appear in about one sample in ten. Most finance journals expect the 5% level, and many researchers now argue for stricter bars because so many patterns have been tested.
There is also very little data. The campaign happens once a year. Even over four decades that gives only about 40 observations on one side of the comparison. Daily stock returns are very noisy, and with so few data points, one or two bad days can create a gap that looks meaningful.
Second problem: cutting up the timeline
Because the result was weak, Vasileiou ran a 2, a statistical method for finding the date when a relationship appears to change. It picked out 1991. From 1984 to 1991 there was no difference between the two kinds of Wednesday. After 1991 there was a difference, but it was still significant only at 10%.
Break-point tests have legitimate uses. In this setting, though, they give the researcher another choice to make. If you split the sample wherever the effect looks strongest, the stronger result in one part is partly built in by that choice.
Third problem: the 3
According to Klement, the result really changed when Vasileiou added control variables, which are extra factors included in a regression to account for other influences on returns. He added three:
The share of UK adults who smoke.
The share of smokers who quit.
The share of UK people who own shares directly.
Klement raises two objections. First, the first two variables are highly correlated, because the smoking rate falls mostly as a result of people quitting. Statisticians call this 4: two predictors carry nearly the same information. The model then has trouble separating their effects, and its estimates and significance tests become unreliable. Klement goes further and says it "invalidates the entire statistical approach." Second, he can see no reason why direct share ownership should affect returns on No Smoking Day at all.
His main point is about what these variables actually are. Two of them fall steadily over time (smokers, direct shareholders) and one rises steadily (quitters). In effect, they work as time trends. Adding smooth trends to a regression can soak up variation and shift significance levels without telling you anything about the mechanism being claimed. With them included, the No Smoking Day gap became significant at 5%. Klement notes drily that 5% is "what every researcher wants to see because now you can submit it to a journal."
Why this is 5
Klement's verdict is that this is data mining, also known as p-hacking: making choices about the sample, the time period and the variables until a result crosses the significance threshold. Here is a hypothetical example of how quickly this adds up. Suppose a researcher could try 20 reasonable versions of the same test: different start dates, break points and sets of controls. Even with no real effect, there is roughly a 64% chance that at least one version would be significant at 5%. The final paper usually reports the version that worked, not the 19 that didn't.
The paper's own chart compares average returns on No Smoking and ordinary Wednesdays, and the gap is visible. Klement's argument is not that the gap is missing from the data. He argues that the route to statistical significance is what makes it unconvincing.
What remains open
Klement's post is short, and it leaves out several details: how large the return difference is, how the regression was specified, and whether the paper has been through peer review or is a working paper. He doesn't show that the effect would disappear under a cleaner test. He argues that the evidence offered doesn't establish it. A natural check would be an out-of-sample test, such as whether the effect holds in years after the study period or in markets with similar campaigns. Nothing like that is reported.
For investors, the lesson goes beyond this one paper. A large share of published anomalies weaken or disappear after publication. Be sceptical of any pattern that only shows up after splitting the time period and adding unrelated trends. It is unlikely to make you money after costs.
Remember
A 10% significance level is weak evidence; roughly one in ten tests of a non-existent effect would pass it.
Adding steadily trending control variables can push results over the 5% bar without explaining anything.
Once-a-year calendar effects rest on very few observations, so they're easy to produce by chance.
Tyler Cowen at Marginal Revolution highlighted a recent paper by Bertrand Achou and co-authors. Its finding: most older Japanese people say they would prefer a nursing home that uses robots for part of the care, and would pay extra for it.
The problem
Japan is ageing fast and doesn't have enough long-term care workers. One proposed fix is caregiving robots and information and communication technology (1), meaning sensors, monitors and other networked devices that take on some caregiving tasks. That only works if residents accept it, and there has been little large-scale evidence on whether they do. Few people have lived with robot care, so you can't watch what they choose. You have to ask.
How the study worked
The researchers surveyed 4,314 Japanese adults aged 55 to 75 online. Each picked between two nursing homes described as identical except for one difference. One used only human caregivers. In the other, robots and ICT handled a substantial share of care in one randomly assigned area: communication, monitoring or 2 (helping people move). Humans did everything else. Respondents also stated their 3 (4), the extra fee they'd accept for the robot-assisted home.
What they found
65% chose the robot-assisted home.
Acceptance depended on the task. It was highest for mobility help, middling for monitoring and lowest for communication. People are happiest handing physical work to machines and least happy handing over conversation.
Average WTP was about 8% above a typical nursing home fee.
People who already knew about caregiving robots were more accepting and willing to pay more. The authors read this as a sign that information could shift preferences.
Answers lined up with respondents' general attitudes toward technology, which suggests they took the survey seriously.
A rough calculation in the paper suggests the benefits of these technologies could far exceed their costs, especially for robots that help with mobility. The abstract doesn't show the numbers behind that estimate.
Caveats
These are survey answers, not real purchases. People often overstate what they'd pay for things they haven't tried. "Otherwise identical" homes don't exist in practice. An online sample may lean toward people who like technology. Respondents topped out at 75, younger than many nursing home residents. The link between awareness and acceptance is a correlation, not proof that information causes it. And as Cowen notes, these are Japanese respondents. Japan is unusually familiar with robots and short of care workers, so the results may not carry over elsewhere.
The takeaway is narrow but useful. People accept robots as an addition to human care for specific physical tasks, not as a replacement for human contact.
Tyler Cowen at Marginal Revolution pointed to a recent paper by Bertrand Achou and co-authors. It asks a question that matters more each year in fast-ageing countries: would older people accept care from robots? Cowen's only comment is that the finding applies to "the Japanese elderly, to be clear." The post is just the paper's abstract, so this write-up covers what the abstract reports and no more.
The problem
Japan's population is ageing, and it lacks enough long-term care workers. That has raised interest in caregiving robots and information and communication technology (1), meaning devices like sensors, tablets and networked monitors that can do some of a caregiver's work. Whether this helps depends partly on supply: what the machines can do and what they cost. It also depends on demand, meaning whether the people being cared for want it. Until now, large-scale evidence on that second question has been scarce.
Demand is hard to measure because few people have lived in a robot-assisted nursing home. You can't simply watch what they buy. So the researchers asked.
How the study worked
The team ran a custom internet survey of 4,314 Japanese people aged 55 to 75. That group is mostly not in care yet, but many soon will be. Each respondent chose between two nursing homes described as identical in every way but one:
Home A: humans provide all of the care.
Home B: robots and ICT handle a substantial share of care in one area, while humans do everything else.
The area was assigned at random. It was one of three:
Communication: talking with and engaging residents.
Monitoring: keeping watch over residents, for example at night.
Mobility assistance: helping residents move, such as getting out of bed or walking.
Randomising the area lets the researchers compare acceptance across tasks without the results being skewed by who happened to get which question. The survey also measured 2 (3), the extra fee a respondent would accept for the robot-assisted home. It also asked general attitude questions about robots and technology.
What they found
65% preferred the robot-assisted home. Most people chose partial automation over all-human care.
A back-of-the-envelope calculation in the paper offers what the authors call "suggestive evidence" that the benefits of introducing robots and ICT could be much larger than the costs, especially for robots that help with mobility. The abstract doesn't give the inputs to that calculation.
Why mobility comes first
The ranking makes intuitive sense. Physical tasks like lifting and transfers are where human help can feel most intrusive and where caregivers face high injury risk. They are also where a machine can make a resident feel more independent. Conversation is the part of care many people value most for its human quality. That would explain why it ranks last.
Caveats
What's left open
The abstract doesn't say how the cost side of the cost-benefit estimate was built. It also doesn't say whether WTP differed much by area, or how the 65% figure splits across areas. More broadly, the study shows people accept robots as an addition to human care for specific tasks, not as a replacement. Whether that acceptance survives contact with real machines in real homes is the next question to test.
Remember
Acceptance depends on the task: people welcome robots for lifting and moving, and resist them for conversation.
People who already knew about care robots liked them more, so familiarity may drive acceptance.
It's a survey of Japanese adults under 75, so real behaviour and other countries could differ.
Gordy Vytlacil, a retiree entering his 80s, posted on HumbleDollar's reader forum about a test he is 30 months into. He wants to know whether his family's discretionary spending can come entirely from a portfolio's dividends and interest. He has reinvested every dividend his whole life. He is changing course now to plan for possible cognitive decline. He wants a setup that needs very few decisions.
Why he can try this
Social Security and annuity payments already cover the couple's essential expenses and much of their discretionary spending. The portfolio only has to provide about 3% a year for travel, gifts and charity. That spending can be cut in a bad year. He says he would not try this earlier in retirement.
How it works
He set aside a $100,000 test account split into three funds:
30% in an S&P 500 index fund, for growth
30% in a fund tracking the 1 (100 US companies with high, steady dividends)
40% in 2, a bond fund that spreads across several kinds of debt
Gains in the stock funds are reinvested. All dividends and interest go into a cash reserve. He takes a fixed amount out of that reserve each month. The reserve started with several months of income as a cushion, because the payouts vary from month to month.
Results
Backtests on 3, an online tool for testing portfolios on past data, suggested about 8% annual growth plus 3.3% income. The live account has done better: 11% growth and 3.8% income, a 14.8% total return. He admits markets were good during this period. Because stocks outran bonds, the 60/40 stock-bond mix has drifted to 70/30. He expects to rebalance about every three years.
Half the couple's money is in Roth accounts, which have no required minimum distributions (4). The RMD is the yearly withdrawal the IRS requires from traditional retirement accounts. That means 3% of the whole portfolio equals about 6% of the traditional half. By our estimate, not his, that is above the roughly 5% required at age 80. The required share keeps rising with age.
Caveats
Thirty months of a rising market is a thin test. Bond income drops when interest rates fall, and companies can cut dividends in a recession. Spending dividends is also economically close to selling the same amount of shares. The real benefit is having fewer decisions to make, not extra money.
He will decide in six months whether to move the whole portfolio to this setup. An advisor or 5 is still an option.
On HumbleDollar's reader forum, retiree Gordy Vytlacil describes a test he is 30 months into. He and his spouse are entering their 80s. He is checking whether a simple portfolio can pay their discretionary spending from dividends and interest alone. If it can, managing the money would take far fewer decisions. He has been a total-return investor all his life, reinvesting every dividend. His reason for changing now is specific: he wants a system that still works if his judgment declines.
The problem he is solving
Most retirees who draw on a portfolio make the same choices over and over. They decide which fund to sell, when to sell it, how much to take and when to rebalance. Each of those choices goes wrong more easily when cognition slips, and the risk of that rises sharply in the ninth decade of life. Hiring help is one answer, and Vytlacil says he has interviewed financial advisors and looked at a 1 (an automated investment service) with a yearly check-in. His other answer is to design a portfolio where spending mostly runs itself.
His situation makes this possible. Social Security and annuity payments cover all essential expenses and much of their discretionary spending. The portfolio only has to supply about 3% a year for travel, gifts and charitable donations. Because the money is discretionary, both withdrawals and spending can flex when markets turn.
How the test portfolio works
He funded a separate account with $100,000 and has not touched it. It holds three funds:
30% S&P 500 index fund, broad US large-company stocks, which he treats as the growth piece.
30% fund tracking the 2, a stock index of 100 US companies selected for high, sustainable dividends.
40% 3, a bond fund that spreads across several kinds of debt.
There are two rules. Gains in the stock funds are reinvested. All dividends and interest go into a separate cash "reserve fund." To mimic a monthly paycheck, he takes a set withdrawal out of the reserve each month. He started the reserve with several months of expected income, so the uneven month-to-month payouts don't leave it empty.
An illustration with numbers that aren't his: at the 3.8% yield the test has produced, a $1 million portfolio would put about $38,000 a year into the reserve, roughly $3,170 a month on average. Some months would pay more than that and some less. The buffer smooths the difference.
Results so far
Before starting, he ran the mix through 4, an online backtesting tool. Historically it delivered about 8% annual growth plus 3.3% in dividend and interest income. The live account has beaten that: 11% annual growth and 3.8% annual income, a 14.8% total return. He notes the past two and a half years were good for markets, though he says the results are in line with history.
The allocation has drifted. Because stocks outran bonds, the original 60/40 split is now about 70/30. He concludes the portfolio might need rebalancing about every third year. That is still one decision every few years, not a stream of them. He also considers starting at 50/50. More bonds would raise current income, slow growth and stretch out the time before rebalancing is needed.
Taxes and 5
About half the couple's assets are in Roth accounts. He says a 3% withdrawal on the whole portfolio also meets their required minimum distributions (RMDs), the yearly withdrawals the IRS requires from traditional retirement accounts. The article doesn't explain why, but the arithmetic is simple. If half the money is in Roths, which have no RMDs for the owner, then 3% of the total equals about 6% of the traditional half. Under the IRS's 6, the required withdrawal at age 80 is about 5% (1 ÷ 20.2). So 6% clears it. That estimate is ours, not his, and it assumes the withdrawals come from the traditional accounts. The required share rises with age, to about 6.25% at 85, so the cushion gets thinner over time.
He also holds alternative assets, mainly bitcoin and precious metals, equal to another 20% on top of the portfolio. He counts them as growth, not income, and keeps them outside this test.
What to make of it
Three points deserve caution.
The sample is short and the timing was good. Thirty months in a strong market says little about how the plan holds up in a long bear market or when interest rates fall. Bond-fund payouts drop when rates fall. Dividend funds can cut payouts in a recession, as many companies did in 2008–09 and 2020.
Income isn't free money. A dividend lowers the fund's share price by the same amount, so spending dividends is economically close to selling the same dollar amount of shares. The real benefits are behavioral: no decisions about what to sell, and a natural cap on spending. The costs are that you can't control how much income arrives, and in taxable accounts you may owe more tax than you would by selling shares.
It works because of his particular finances. It works because guaranteed income covers the essentials and the portfolio pays only for spending that can be cut. Vytlacil says he would not do this earlier in retirement. For someone who relies on the portfolio for rent or groceries, a drop in income is a much bigger problem.
What's still open is his own verdict. In six months he plans to analyze the monthly cash flow, test a few what-if scenarios and decide whether to move the whole portfolio to this setup. He hasn't ruled out an advisor or robo-advisor. His instinct for now is that if this is "enough," it is "good enough."
Remember
Spending only the income works best when guaranteed income already pays for necessities and the portfolio covers spending you can cut.
A dividend lowers the share price by the same amount, so the main gain is fewer decisions, not extra money.
Because stocks outrun bonds, a 60/40 mix drifted to 70/30 in 2.5 years, so plan to rebalance occasionally.
Coupons and 3, meaning charging different people different prices. Coupons only sort customers if some people don't bother to look for them. If every agent finds every coupon, that sorting disappears.
4. Today people who forget to cancel subscriptions subsidize those who remember. Agents won't forget. Collison admits he can't say who ends up better or worse off overall.
Quality over distribution. A better product often loses to a familiar brand because nobody hears about it. Collison asks what markets would look like if everyone spent "at least 10 hours researching their purchases." He argues agents act as a "structural subsidy for product quality," and that this makes data on quality more valuable.
5. Many internet companies earn money by deciding which seller a shopper sees first, through placement fees and ranking algorithms. That business relies on people clicking the top result. Collison expects big changes here but doesn't predict their direction.
7. Many internet companies make money by deciding which seller a shopper sees first, and they rely on people clicking the top result. Sellers pay placement fees and try to please ranking algorithms. Collison says not all of this is wasted, since a seller's willingness to pay for placement tells buyers something. But it isn't efficient. If agents rather than distracted humans do the clicking, the value of that routing could change a lot. He doesn't predict which way. For a reader thinking about business models, this is the part that bears on search and marketplace companies.
Whose side is the agent on? Everything above assumes the agent serves the consumer. Collison suspects that will be the winning strategy but leaves the question open. An agent that takes referral fees from merchants would bring back the very bias it is supposed to remove.
Acceptance depended on the task. It was highest for 4, in the middle for monitoring, and lowest for communication. The abstract doesn't give the percentage for each area. The pattern is easy to read, though: people are most willing to hand over physical work, and least willing to hand over companionship.
Average WTP was about 8% above a typical nursing home fee. As an illustration only: if a home charged ¥200,000 a month, that would be roughly ¥16,000 extra.
People who already knew about caregiving robots were more accepting and willing to pay more. The authors say this suggests information could shape preferences.
Answers fit together. People who said they felt positive about robots in the attitude questions also tended to pick the robot home and pay more for it. The authors treat this as a sign that respondents answered seriously and consistently.
These are 5. Saying you'd pay 8% more in a survey is different from paying it. People also tend to overstate how much they'd pay for things they haven't experienced.
"Otherwise identical" is an assumption. In real life, robot-assisted homes may differ in staffing, price, quality or reliability. Respondents were choosing a stylised option, not a real facility.
An internet survey may lean toward tech-friendly people. People comfortable answering online may like technology more than older people in general.
The age range stops at 75. Many nursing home residents are older and frailer than that, and their views could differ.
The awareness link is a correlation. Knowing about robots goes with liking them, but the causation could run the other way, or both could stem from a general interest in technology. The authors say "potential role," not proof.
Japan may be unusual. Cowen's "to be clear" points to this. Japan has a long cultural familiarity with robots and a particularly severe care worker shortage, so the results may not carry over to the US or Europe.