Illiquid Millionaires and a Trillion-Dollar Data Center Bet · Morning Gist
Wednesday, November 45 stories · 16 min
Illiquid Millionaires and a Trillion-Dollar Data Center Bet
Today's pieces test familiar stories about wealth, AI spending, tipping, IPO lock-ups and rents against the actual numbers, and several turn out less simple than advertised.
Picked from 18 new articles across 16 sources · arrow keys for other days
Today in 30 seconds
30s left
About 29 million US households are millionaires, a share more than doubled since 1998, but the median one is 63 and mostly illiquid. story 1 ↓
AI-driven data center investment has reached double its normal share of US GDP, with six listed companies spending at a $1 trillion annual pace. story 2 ↓
Firms claw back about a third of tips, a 20,000-firm study finds, yet workers still gain as demand surges lift revenue nearly twice as much. story 3 ↓
IPO lock-up expiries didn't sink the typical stock across 330 deals: median shares beat an S&P 500 fund by 0.7%, though 154 fell. story 4 ↓
US asking rents rose 0.1% to a $1,384 median on Apartment List, the first annual gain in over three years; Realtor.com's measure still falls. story 5 ↓
Almost half of Ireland's corporation tax comes from just three companies: Apple, Eli Lilly and Microsoft.
1/5Of Dollars and Data· Nick Maggiulli· Nov 3
About 29 Million U.S. Households Are Millionaires, but Few Have Liquid Millions
Nick Maggiulli's reading of 2025 Federal Reserve survey data: 21.5% of U.S. households have $1 million in net worth, but only 6.1% have it in assets they could readily spend.
Why it matters · It gives you fairer benchmarks: comparing your own balance sheet to "millionaires" means little until you match the definition of wealth and the age group.
Know this first
Context from the editor, not the article · 19 sec
1 · The data source
The Survey of Consumer Finances is a Federal Reserve survey run every three years. It records U.S. households' assets, debts and income in detail, which makes it a standard source for studying wealth over time.
2 · Net worth versus spendable money
Net worth counts everything owned minus everything owed. Some of it is hard to spend: home equity requires selling or borrowing, and retirement accounts such as a 401(k) often carry restrictions or penalties before a certain age.
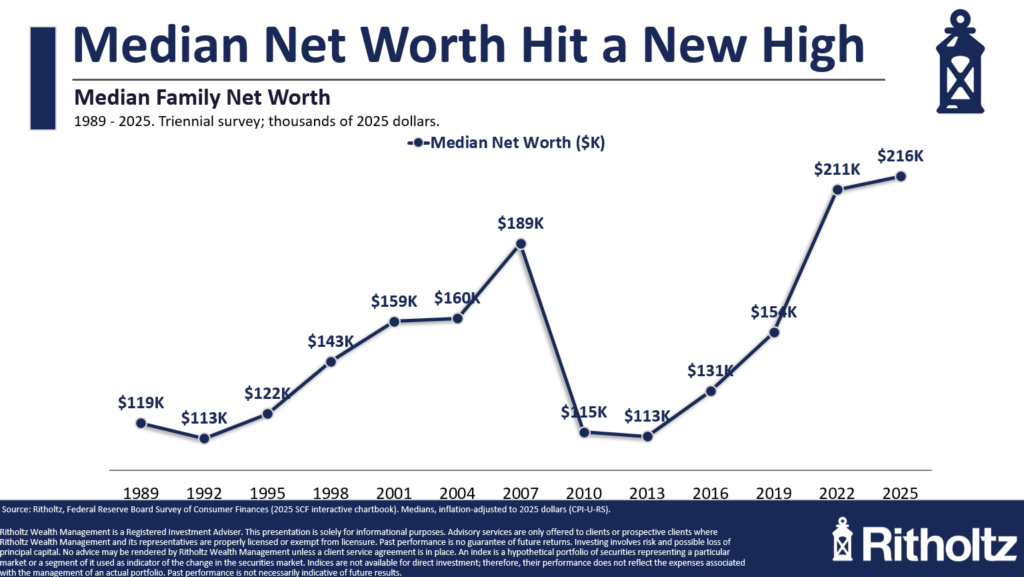
Share of U.S. households with $1M+ under each definition, 1989–2025, including the 2007–2010 divergence.1 / 4
2/5The Overshoot· Matthew C. Klein· Nov 3
AI-driven U.S. data center investment reaches double its normal share of GDP
U.S. spending on computers, telecoms gear and data center buildings reached 2.5% of GDP, about double its norm. Six big tech companies drive much of it, and private AI labs are preparing to add more.
Why it matters · An investment surge this large and concentrated can shape U.S. growth figures and the fortunes of a few giant companies that weigh heavily in many investors' index funds.
Know this first
Context from the editor, not the article · 19 sec
1 · Why AI needs data centers
Training and running large AI models takes specialized processors, memory and networking gear, housed in huge powered and cooled buildings. Few companies can fund this, so many AI developers rent capacity from cloud providers.
2 · Capex versus everyday costs
Capital expenditure buys long-lived assets such as servers and buildings. Rather than counting the full cost immediately, companies generally spread it over the asset's useful life as depreciation, so heavy spending today can weigh on reported profits for years.
Chart from the article's opening section on data center-related business investment and its pre-ChatGPT trend.1 / 3
3/5Marginal Revolution· Tyler Cowen· Nov 3
Firms claw back about a third of tips, yet workers still gain
Economists linked sales and payroll data at 20,000 US firms. Adopting tipping cuts base wages 23–33 cents per tip dollar, but tips spur effort, and a model suggests workers and firms both gain.
Why it matters · It treats tipping as customer-funded commission, which explains who really keeps a tip dollar and why tip prompts keep spreading to new businesses.
Know this first
Context from the editor, not the article · 29 sec
1 · How US tipped pay works
US federal law lets employers pay tipped workers as little as $2.13 an hour if tips bring them to the $7.25 minimum wage. Some states require more, and many tipped workers earn well above these floors.
2 · Who really gets a payment
Economists call this incidence: the person handed the money may not keep all of it. A tip goes to the worker, but if the employer then lowers base pay, part of its value passes to the firm.
3 · Why demand shocks are useful
Comparing tipping and non-tipping firms directly is misleading because they differ in many ways. Researchers therefore look for outside jolts to customer demand, then compare how each type of firm responds to the same kind of surge.
4/5HumbleDollar· Daniel Oliveira· Nov 4
IPO lock-up expiry didn't sink the typical stock, study of 330 deals finds
Equibles examined recent IPOs and found the typical stock did not fall when insiders' six-month ban on selling ended. Trading volume rose more than prices moved, and the deal terms varied more than expected.
Why it matters · It tests a popular market fear against recent data, and shows why a widely known, scheduled event may be a poor reason to change an investment decision.
Know this first
Context from the editor, not the article · 26 sec
1 · What a lock-up is
Before an initial public offering, insiders and early investors usually agree not to sell shares for a set period. The restriction stops a flood of stock reaching the market just after the company lists.
2 · Where the terms appear
Companies going public must file a prospectus with the Securities and Exchange Commission. This public document discloses the lock-up's length and who it covers, so investors can know the release date months ahead.
3 · Why median and benchmark matter
A median is the middle result, so a few extreme moves don't distort it. Comparing with an S&P 500 fund strips out the market's general rise or fall during the same days.
5/5Calculated Risk· CalculatedRisk by Bill McBride· Nov 3
US asking rents post first annual rise in over three years
Apartment List reports US rents on new listings up 0.1% from a year ago as a record apartment supply gets absorbed. Bill McBride says they have likely bottomed, though Realtor.com's measure still shows declines.
Why it matters · Rents on new leases tend to show up in official inflation about a year later, and they shape what renters can negotiate and how landlords earn money.
Know this first
Context from the editor, not the article · 27 sec
1 · Advertised versus paid rent
Listing-based rent data tracks prices offered to people signing new leases. Most tenants are mid-lease or renewing, so the average rent actually paid moves more slowly and turns later than advertised prices.
2 · The apartment supply cycle
Apartment buildings take years to finish, so supply arrives long after developers decide to build. Vacant new units push landlords to compete on price until demand fills them and fewer new projects open.
3 · Why rent indexes disagree
Private rent indexes differ in geography, sample and method. Some follow median listing prices in particular markets, while others try to track price changes across comparable units, so they can briefly point in different directions near a turning point.
About 29 million U.S. households, or 21.5%, now have a 1 above $1 million, according to Nick Maggiulli's analysis of the 2025 2, the Federal Reserve's survey of household balance sheets. After adjusting for inflation, that share has more than doubled since 1998.
But most of those households don't have $1 million they could readily spend.
Four ways to count a millionaire
Maggiulli, who writes the blog Of Dollars and Data, compares four definitions:
Net worth: all assets minus all debts. This is the classic test.
Net worth excluding home: also removes 3, the home's value minus its mortgage.
Net worth excluding home and retirement: also removes retirement accounts.
Liquid net worth: non-retirement financial assets minus debts other than a mortgage. Maggiulli calls this what you could write a check for.
Here is an illustrative household, not one from the article. It has $500,000 in home equity, $600,000 in a 4 retirement account, $150,000 in a brokerage account and a $20,000 car loan. Its net worth is $1.23 million, so it counts as a millionaire. Remove the home and it has $730,000. Remove the 401(k) too and it has $130,000.
That pattern shows up nationally. Excluding home equity and retirement accounts cuts the number of millionaire households by more than half. On 5, the share falls to 6.1% of households, so only about 28% of millionaires qualify.
The share has risen under every definition, especially over the last six years. Housing can distort the count, though. From 2007 to 2010, the net-worth share fell while the share excluding homes rose, which Maggiulli reads as inflated house prices having temporarily swelled the total.
Most are modest millionaires
About 44% of millionaire households have $1 million to $2 million, and 77% have under $5 million. Their wealth also looks different from that of the very rich:
$1M–$2M households: home equity is about 33% of combined wealth, and private businesses about 5%.
$10M+ households: home equity is about 7%, and private businesses about 33%.
Maggiulli warns against reading this as a recipe. Plenty of people start businesses and buy stocks without getting that rich, and we mostly see those who succeeded.
It's largely about age
Only 2% of households under 35 and 13% of those aged 35–44 are millionaires, compared with over 30% of households 55 and older. The median millionaire household is 63. Maggiulli argues that comparing yourself to millionaires isn't fair unless you are around their age.
He also rejects the social media line that $1 million isn't much: 6 puts that sum in the top 1.5% of adults worldwide.
The article doesn't break down how much of the rise since 1998 comes from asset prices, saving or an aging population.
About 29 million U.S. households have a 1 above $1 million, according to Nick Maggiulli's analysis of the 2025 2, the Federal Reserve's survey of household assets and debts. That is 21.5% of all households. Measured in inflation-adjusted dollars, the share has more than doubled since 1998, so the rise isn't simply a matter of prices making $1 million easier to reach.
Maggiulli, who writes the blog Of Dollars and Data, argues that the headline number hides a basic question: what counts as being a millionaire? Someone with a $1 million home and $10,000 in checking meets the classic test, yet may not feel rich or be able to spend much.
Four definitions, four answers
He measures the population four ways:
Net worth: everything you own minus everything you owe.
Net worth excluding home: net worth minus 3, meaning the value of your primary residence less any remaining mortgage.
Net worth excluding home and retirement: also removes retirement accounts, on the argument that this money is earmarked for later and shouldn't count as ordinary wealth until retirement age.
Liquid net worth: non-retirement financial assets minus debts such as credit cards and auto loans. Maggiulli calls this what you could write a check for. It excludes private business equity and other real estate. He leaves mortgage debt out because it is long term and has already been handled in the other definitions, a change from how he has defined the measure before.
Two illustrative households, not taken from the article, show how these definitions separate.
Household A has $500,000 in home equity, $600,000 in a 4 retirement account, $150,000 in a brokerage account and a $20,000 car loan:
Definition
Household A
Net worth
$1,230,000
Excluding home
$730,000
Excluding home and retirement
$130,000
Liquid net worth
$130,000
Household A is a millionaire only under the first definition. Household B rents, has no retirement savings, owns a private business worth $1.5 million and keeps $50,000 in cash. It is a millionaire under the first three definitions, but its 5 is just $50,000. That is why the third and fourth measures can differ.
Nationally, removing home equity and retirement accounts cuts the number of millionaire households by more than half. On liquid net worth, the share falls from 21.5% to 6.1% of households, which implies roughly 8 million households. Only about 28% of millionaires by the classic measure are also millionaires by the liquid one. Maggiulli says there is nothing wrong with this, but it shows how much of this wealth is tied up in illiquid assets.
The trend, and what housing did to it
The share of millionaire households has risen under all four definitions, particularly in the last six years. The absolute jump in households above $1 million during that period is the most striking change in the data going back to 1989, in Maggiulli's view.
The detail he finds most telling is 2007 to 2010. Over those years, the share of millionaires by net worth fell while the share by net worth excluding the home rose. He reads this as evidence that an inflated asset class, in this case U.S. housing in 2007, can temporarily distort the count. Households near the line can cross it on paper because of a house price, then drop back when that price falls.
Millionaires aren't one group
There are nearly 10 times as many households with $1 million to $10 million as there are 6, those with more than $10 million. Within the millionaire population, 44% have $1 million to $2 million, and 77% have less than $5 million. Maggiulli describes this as an extreme 7: many households sit just past the threshold and a thin tail stretches far above it.
What people own shifts as wealth grows, with more in businesses and stocks and less in home equity and retirement accounts:
Share of combined wealth
$1M–$2M
$10M+
Home equity
~33%
~7%
Private businesses
~5%
~33%
It is tempting to read this table as instructions, and Maggiulli cautions against that. Correlation isn't causation, and starting a business and buying stocks guarantees nothing. He points to 8, which means seeing mainly the winners and missing those who took the same risks and failed. It gets stronger further up the wealth scale. There is also a plain mechanical reading, which is ours rather than his: a house can only get so large relative to a fortune, so at very high wealth other assets must make up most of it.
Age explains a lot
Only 2% of households under 35 are millionaires, and 13% of households aged 35–44. Among households 55 and older, the figure is over 30%. The median millionaire household is 63, so half are older than that.
Maggiulli's advice follows from this: if you benchmark yourself against millionaires, make sure you are around their age. People with ten or more extra years of saving and compounding aren't a fair comparison. His analogy is measuring a kindergartner's strength against a teenager's.
Even across all ages, millionaires remain a minority. Using 9, his own scheme for sorting households into net-worth bands, around 78% of households are in Level 3 ($100,000 to $1 million) or below.
He also pushes back on social media claims that $1 million isn't much. 10 places $1 million in the top 1.5% of adults worldwide, and $100,000 in the top 17%.
What the numbers don't settle
The article doesn't name a correct definition. Maggiulli presents the data and leaves readers to choose. Each measure has limits. Net worth treats a house you live in like cash, while the liquid measure ignores retirement savings that may be a retiree's main source of income. None of the four, as described, adjusts for taxes owed when money leaves a pre-tax retirement account, or for local living costs.
Two other gaps are worth keeping in mind. The article doesn't separate how much of the rise since 1998 comes from higher asset prices, more saving or an older population, although the age figures suggest demographics could matter. The global comparison also mixes units: the U.S. figures count households, while the UBS ranking counts adults, so a couple sharing $1 million isn't the same as one adult holding it.
Remember
Which definition you use changes the answer more than threefold: 21.5% of households by net worth, 6.1% by liquid net worth.
A house-price boom can create paper millionaires: the net-worth share fell during 2007–2010 while the ex-home share rose.
Compare yourself with households your own age: 2% of under-35s are millionaires, against over 30% of those 55 and up.
U.S. business spending on computers, telecoms equipment and the construction of 1 (the buildings, before the equipment goes in) is running more than 100% above its pre-ChatGPT trend, Matthew C. Klein reports in his economics newsletter, The Overshoot.
In the third quarter of 2026, this investment equalled 2.5% of 2, the dollar value of everything produced in the U.S. That is roughly double the steady 1.3% average of 2009 to 2024. Klein says the speed stands out most, with much of the rise coming since the end of 2024.
Software is the exception. Business investment in software is still growing at its pre-ChatGPT pace, so the boom is showing up in hardware and buildings instead.
Who is spending
Klein attributes much of the increase to six listed "3", operators of computing infrastructure at enormous scale: Amazon, Google, Meta, Microsoft, Oracle and SpaceX. Together they are worth about $13.6 trillion.
Their 4, spending on long-lived assets, has grown sevenfold on a quarterly basis since ChatGPT launched in late 2022, and has tripled since the start of 2025. In 2026Q3 it hit an 5 of $1 trillion, meaning the quarter's pace multiplied by four. That works out to about $250 billion a quarter, up from roughly $83 billion in early 2025 (our arithmetic).
Amazon and Oracle focus on selling computing capacity to others. The other four also build proprietary "6", the industry's word for processing capacity, for their own AI labs.
Two big buyers not in the data
The six are only the hyperscalers with roughly comparable audited accounts. Anthropic and OpenAI are not yet publicly listed. Both are 7 of compute, using more than they supply, and mostly create demand by renting from the six.
Klein expects that to change. Anthropic's 8, the filing a company makes before an initial public offering, says it is pursuing its own dedicated data center infrastructure to reduce its dependence on cloud providers. The plans include long-term site leases, buying some equipment directly and arrangements involving dedicated power generation. It expects capital spending "to increase significantly".
Where the money goes
Klein says the money has flowed mostly to six equipment makers: Broadcom, Micron, Nvidia, Samsung Electronics, SK Hynix and TSMC. Three are based abroad. That suggests a caveat of our own: GDP subtracts imports, so the 2.5% figure shows the scale of the investment, not its net boost to U.S. output.
What's missing
The public text stops here, just as the supplier section begins. We can't report what Klein concludes about suppliers or what "changing shape" in his title refers to. The available portion also doesn't address returns, financing or how long the boom can last.
U.S. business spending on computers, telecoms equipment and the construction of 1 (the buildings, before the equipment goes in) is running more than 100% above its pre-ChatGPT trend. That figure comes from an update by Matthew C. Klein in The Overshoot, his economics newsletter. Put simply, spending is more than double what the earlier growth path would have produced by now.
A second measure tells a similar story. In the third quarter of 2026, this investment equalled 2.5% of 2, the dollar value of all goods and services produced in the U.S. From 2009 to 2024, the share held steady at an average of 1.3%. As a rough sense of scale, if GDP is about $32 trillion (our estimate, not Klein's), 2.5% is roughly $800 billion a year.
Klein says the level is less striking than the speed: much of the rise has come just since the end of 2024.
Software breaks the pattern. Business investment in software has kept growing at its pre-ChatGPT pace, which Klein calls intriguing. On these numbers, the boom is showing up in hardware and buildings rather than in company software budgets. The article's public text does not explain why.
Six companies carry much of the load
Klein attributes much of the extra spending to six listed "3", operators of computing infrastructure at enormous scale: Amazon, Google, Meta, Microsoft, Oracle and SpaceX. SpaceX belongs on the list because it merged with Elon Musk's AI company xAI earlier in 2026. Together, the six have a market value of roughly $13.6 trillion.
Their 4, spending on long-lived assets, has grown sevenfold on a quarterly basis since ChatGPT launched at the end of 2022. It has tripled just since the start of 2025. In 2026Q3, it ran at an 5 of $1 trillion, meaning the quarter's pace multiplied by four.
Working backward gives a clearer picture (our arithmetic from Klein's rounded multiples):
Period
Approximate quarterly capex
End of 2022
$36 billion
Start of 2025
$83 billion
2026Q3
$250 billion
The current pace equals a little over 7% of the group's combined market value each year.
The six are not all pursuing the same business. Klein says Amazon and Oracle have chosen to focus on selling computing capacity to others. The other four also invest in proprietary "6", the industry's word for processing capacity, to support their own AI labs. The first approach depends on outside customers, while the second also serves internal AI work.
The $1 trillion and 2.5% of GDP figures should not be compared directly. The first is six companies' reported spending, which can include projects outside the U.S., while the second is a national measure of business spending by category. The available text does not reconcile them.
The spending the data misses
Klein stresses that the six are simply the hyperscalers with roughly comparable audited financial statements. Two more, Anthropic and OpenAI, are not yet publicly listed. Both are 7 of compute, using more than they supply, and they currently drive demand indirectly by renting from the six.
Klein expects them to become significant direct buyers of data center equipment too. He points to the 8, the registration document a company files with U.S. regulators before an initial public offering, from Anthropic. It says the company wants to reduce its dependence on cloud providers, address limits on available compute and secure capacity at the scale needed to develop its most advanced models.
The filing describes several pieces of that plan:
Sites: long-term leases and partnerships with third parties for real estate, power and facilities, with specialist operators managing the buildings.
Equipment: buying some compute and infrastructure gear directly and running it in dedicated facilities built to Anthropic's specification.
Energy: arrangements involving dedicated power generation, and possibly developing, operating or controlling power stations or other energy infrastructure.
Anthropic says its commitments are already "substantial" and that it expects capital spending "to increase significantly".
This matters for reading the data. If the labs move from renting to buying, company-level tracking of the listed six will capture a smaller part of the boom until the labs publish comparable accounts.
Where the money lands
Klein writes that the spending has flowed mostly to a handful of manufacturers that capture much of the value in the equipment inside data centers and connecting their server racks: Broadcom, Micron, Nvidia, Samsung Electronics, SK Hynix and TSMC.
Three of those six are based outside the U.S.: Samsung and SK Hynix in South Korea, and TSMC in Taiwan. That points to a caveat of our own. GDP subtracts imports, so spending on imported equipment does not add to U.S. output one for one. The 2.5% figure therefore shows the scale of the investment, not its net contribution to growth. The available text does not estimate how much of the spending leaks abroad.
What the available text leaves open
The public version stops just as the section on suppliers begins, under the heading "When Unlimited Demand Meets Finite Supply". The rest is behind a "Read more" cutoff. We can't report what Klein concludes about suppliers, or what he means by the "changing shape" in his title.
The available text also doesn't address whether the investment will earn an adequate return, how it is being financed, or how long it can continue. It establishes the size, speed and main buyers of the boom, but not whether the spending will pay off.
Remember
Data center-related investment has moved far above trend while software investment has not, so the surge is physical so far.
Tracking listed companies undercounts the boom, because private labs' spending lacks comparable audited figures.
Spending as a share of GDP measures scale, not net growth, because imported equipment is subtracted from GDP.
Tipping keeps spreading, but there has been little evidence on what it does to workers and firms. A new working paper by economists Dylan Balla-Elliott and Isaac Norwich, highlighted by Tyler Cowen on his blog Marginal Revolution, offers some. Only the abstract is available here, so the details of the method aren't covered.
Following the dollar
Who keeps a tip is hard to see, because employers can respond by cutting the 1, the hourly pay set before tips. The authors linked 2, the transactions from a checkout system, with payroll records at 20,000 US firms. That lets them trace tips from the customer's payment to the worker's earnings.
Tips turn out to be a nearly constant share of revenue, so hourly pay moves with sales, much like a commission.
Firms that start collecting tips claw back 23 to 33 cents of each tip dollar through lower base wages. As an invented example, take a shop paying $18 an hour that adds tipping worth $10 an hour. Base pay would fall to between $14.70 and $15.70, leaving total pay at $24.70 to $25.70. The worker gains, but by less than the full tip.
Do tips change effort?
To test this, the authors built 3, sudden shifts in customer demand, from what customers spend at other businesses. Spending elsewhere is less likely to reflect a firm's own decisions than its own sales would, though the abstract doesn't describe the construction.
The shocks raised revenue nearly twice as much at tipping firms as at non-tipping firms. Base wages and prices didn't respond, so price increases can't explain the gap.
Hours rose by more at tipping firms, and so did 4. The second result is the telling one, since adding hours might be expected to make each hour less productive. The authors conclude that effort drives the gap: workers earn more by serving more customers, each becomes more productive, and the firm expands.
Who wins
Not every firm adopts tipping, and the authors say that's because the gain is smaller where customers tip less. Where customers are prone to tip, a model tuned to the demand-shock results implies 5 rises by about half and firm profit by about 30%. Job value isn't defined in the abstract, but it usually means what a job is worth to a worker compared with the alternatives.
Those two figures are model outputs, not direct measurements. The abstract also reports no estimate of how customers fare, though they pay the tips. The authors say only that these gains "may" explain tipping's recent growth.
Tipping is large and growing, but there has been little evidence on what it does to workers and firms. A new working paper by economists Dylan Balla-Elliott and Isaac Norwich tries to fill that gap. Tyler Cowen highlighted its abstract on his blog, Marginal Revolution, and noted that Norwich is on this year's academic job market from the University of Chicago. Only the abstract is available here, so the details of the method and the precision of the estimates aren't covered below.
The problem
Two questions are hard to answer with ordinary data. The first is who really keeps a tip. A customer hands a dollar to a worker, but an employer can respond by paying a lower 1, the hourly pay set by the firm before tips. The second is whether tips change behavior or merely move money around.
Answering either requires following the same dollar from the customer's payment to the worker's paycheck. The authors do that by linking two kinds of records at 20,000 US firms: 2, the transactions captured by a business's checkout system, and payroll data, which show what workers were paid.
Tips behave like a commission
The first finding is a simple regularity: tips are a nearly constant share of revenue. So a worker's hourly pay rises and falls with the firm's sales, much as a salesperson's commission does.
Here is an illustration, using invented numbers. A server handles $50 of sales an hour, and customers tip 20%, or $10. If the server handles $60 an hour instead, tips rise to $12. The firm hasn't changed anything, yet serving more customers has earned the worker another $2 an hour.
The clawback
Firms that begin collecting tips don't let workers keep the whole gain. They claw back 23 to 33 cents of each tip dollar through lower base wages.
Continuing the illustration, suppose a shop pays a flat $18 an hour and then adds tipping that brings in $10 an hour. The clawback implies base pay falls by $2.30 to $3.30, to between $14.70 and $15.70. Total pay rises to between $24.70 and $25.70. The worker is still ahead by $6.70 to $7.70, not the full $10.
This means a tipped job's lower wage isn't straightforward evidence that workers are worse off, and it also means that a tip isn't purely a transfer to the worker.
Testing whether tips change effort
Higher pay alone doesn't show that tips make people work harder. To test that, the authors build 3, sudden shifts in customer demand, from what customers spend at other businesses. The abstract doesn't give the construction. The general appeal of this kind of design is that spending elsewhere is less likely to reflect a firm's own decisions than its own sales would.
Four results follow from those shocks:
Revenue: the same kind of shock raises revenue nearly twice as much at tipping firms as at non-tipping firms.
Base wages and prices: neither responds. So price increases can't explain the larger revenue gain, and the extra pay reaches workers through tips, not raises.
Hours: they rise by more at tipping firms.
Output per hour: it also rises by more at tipping firms.
The combination of the last two results is the crucial piece of evidence. A business that adds hours in response to busier times might expect each extra hour to be less productive. Here hours and 4 both rise by more, which the authors read as workers putting in more effort when they earn more by serving more customers.
Their account runs as follows. Each worker becomes more productive, so the firm finds it worthwhile to expand, and it also recovers about a third of the tips through lower wages.
Why every firm doesn't tip
If tipping helps both sides, every firm might be expected to adopt it. The authors say the gain is smaller where customers tip less, which would explain why adoption stops short of universal. A weak tipping norm provides a weaker incentive for effort and less money to share.
The size of the gains
The headline welfare numbers come from a model, a stylized version of the economy tuned to match the demand-shock estimates, rather than being directly measured. In firms where customers are prone to tip, the model implies:
Job value up about half: the abstract doesn't define this, but in labor economics it usually means how much a job is worth to a worker compared with the alternatives.
Firm profit up about 30%.
The authors suggest these gains "may" explain why tipping has recently grown in many industries. That is a hedged claim, not a demonstrated cause.
What to keep in mind
The abstract leaves several questions open:
Customers: the stated gains are for workers and firms. The abstract reports no estimate of what customers gain or lose, though they pay the tips. It also doesn't address tipping fatigue or social pressure.
Scope: the large gains apply to firms where customers are prone to tip, so they don't extend to any business that adds a tip screen. Firms that chose to adopt tipping may also differ from those that didn't.
Who shares in tips: the abstract doesn't break results out by role, such as servers versus kitchen staff, or by whether tips are pooled.
Evidence and review: the sample's representativeness and the design behind the clawback estimate aren't described. Cowen's post also offers no view of his own on the paper and doesn't say whether it has been peer-reviewed.
The takeaway that holds up best is the distinction between the pieces. The clawback range and the demand-shock responses are empirical estimates. The size of the benefit to workers and firms rests on the model built on top of them.
Remember
A lower base wage at a tipped job partly reflects the tips themselves: firms offset roughly a quarter to a third.
Tips act as an incentive: when demand rose, output per hour increased more at tipping firms even as hours grew.
Tipping's payoff depends on customer habits, so adding a tip screen won't produce the same gains at every business.
The end of an 12 has a reputation as a danger date, but recent data suggests the typical stock gets through it fine. An IPO, or initial public offering, is a company's first sale of shares to the public. A lock-up is the promise by insiders not to sell for a set period afterward.
3, which processed the data, read the terms in 440 IPO 4, the disclosure documents filed with the Securities and Exchange Commission, from January 2024 to October 2026. Daniel Oliveira summarized the study on HumbleDollar.
The worry
The logic is supply and demand. Founders and early investors may be sitting on large stakes they couldn't sell. When the ban ends, a wave of shares could hit the market and push the price down.
What happened
Across 330 standard lock-ups, the study looked at the three trading days around expiry:
The 5, the middle result, beat an 6, a basket of 500 large US companies, by 0.7%.
154 of the 330 stocks fell, about 47%.
Trading volume moved more than price. In deals on the larger exchanges where substantially all holders were locked up, it ran about 1.34 times the prior month's average.
Oliveira's explanation is that the date is printed in the prospectus months ahead, so anyone expecting selling can trade before it. In other words, a known event may already be in the price.
The terms matter more
Six months is still the norm, covering 392 of the 440 deals. But two details vary widely:
Early selling. Among the 43 IPOs with the most first-month trading, 14 let some locked shares sell early. Among the 320 with the least, only 3 did. So the printed date may not be the first day insiders can sell.
Who is bound. On the 7, Nasdaq's smallest listing tier, 154 of 180 lock-ups cover only directors, officers and the largest shareholders. Other holders could sell from day one.
Oliveira's conclusion is to read the terms rather than watch the calendar.
The limits
This isn't proof that the date is safe. Nearly half the stocks fell, and a median says nothing about how bad the worst drops were. A three-day window also can't capture any selling in the weeks before expiry, which is when Oliveira suggests prepared traders would act.
The HumbleDollar post gives only a short summary, with no averages or longer-term returns. The sample also covers less than three years. It is better read as evidence against a blanket rule of selling before expiry than as a reason to ignore the date entirely.
Investors often circle the end of an 12 as a danger date. An IPO, or initial public offering, is a company's first sale of shares to the public, and a lock-up is the promise by insiders not to sell for a set period afterward. A study by 3, summarized on HumbleDollar by Daniel Oliveira, read the terms in 440 IPO 4, the disclosure documents filed with the Securities and Exchange Commission, from January 2024 to October 2026. It then checked what happened to prices.
Its headline result: across 330 standard lock-ups, the typical stock did not fall around the expiry date.
Why the date looks dangerous
The fear rests on simple supply and demand. Founders, employees and early investors may hold large stakes they have been unable to sell. When the restriction ends, those shares can reach the market all at once, and more supply should push the price down.
There is also historical support for some caution. Outside this study, a well-known paper by Field and Hanka (2001), covering IPOs from 1988 to 1997, found an average three-day abnormal return of about -1.5% around expiry, with volume up about 40%. That is an average from a different era, so it isn't directly comparable with the new median figure.
What the new numbers show
The test used a three-trading-day window around the end of each lock-up and compared each stock with an 5, a basket tracking 500 large US companies.
Price: the 6 beat the fund by 0.7%. As an illustration, a stock up 1.0% over those days while the fund rose 0.3% would be 0.7% ahead.
Direction: 154 of the 330 stocks fell, or about 47%. The post doesn't say whether "fell" means in absolute terms or relative to the fund.
Volume: in deals on the larger exchanges where substantially all holders were locked up, trading volume ran about 1.34 times the prior month's average.
So more shares changed hands, but the typical price didn't suffer. Oliveira's explanation is that the date is printed in the prospectus months ahead, so anyone expecting selling can trade before it. Put another way, a known event may already be reflected in the price by the time it arrives. A rise in volume also doesn't by itself mean a price drop, because every seller needs a buyer.
The terms differ more than the calendar suggests
Six months remains the norm: 392 of the 440 prospectuses, or 89%, lock up insiders for 180 days or six months. The differences lie elsewhere.
Early release. Among the 43 IPOs with the most trading in their first month, 14 let some locked shares sell early. Among the 320 with the least trading, only 3 did. That is about a third versus about 1%. For a heavily traded new stock, then, the headline expiry date may not be the first day insiders can sell. The post doesn't describe the conditions for early sales.
Who is bound. On the 7, the smallest of Nasdaq's three listing tiers, 154 of 180 lock-ups bind only directors, officers and the largest shareholders. Other holders in those deals could sell from day one. My inference, not a finding reported in the post, is that the expiry date may release a smaller share of the stock in such deals, since some of it was never restricted.
What to do with this
Oliveira's lesson is to read the terms rather than watch the calendar. Two questions matter: who is actually locked up, and can any of them sell early? Both are answered in the prospectus.
The data doesn't show that the date is safe for any individual stock. Nearly half of them fell, and a median of 0.7% says nothing about how large the worst drops were. It is better read as evidence against a blanket rule of selling before expiry.
What the summary leaves open
The post is a brief summary of a longer linked study, and it omits several things a careful reader would want:
The spread of outcomes: it gives no average return or range around the median.
The longer term: a three-day window can't show whether prices drifted in the weeks before or after expiry. If traders sell ahead of the date, as Oliveira suggests, any weakness would fall outside that window.
The sample: it doesn't explain how the 330 "standard" lock-ups were chosen from the 392 six-month deals. The 43 and 320 trading groups also leave 77 IPOs unmentioned.
The period: the sample covers less than three years, a short span for judging a market pattern.
Practical gains: a typical edge of 0.7% over three days isn't evidence of a profitable trade, and the post doesn't test one.
Remember
Early-release clauses were far more common among heavily traded IPOs: about a third, versus about 1% of the least traded.
A publicly scheduled event is hard to profit from or fear blindly, because traders can act well before it.
A favorable median doesn't make an individual stock safe; 47% of these stocks still fell around expiry.
Chart accompanying Apartment List's report of rents turning positive and vacancies tightening; the excerpt doesn't describe it further.1 / 2
Rents on newly listed US apartments have stopped falling, at least on one closely watched measure. 1, a rental-listing site that publishes a monthly national report, puts its median rent at $1,384, up 0.1% from a year earlier. It is the first positive year-over-year reading in more than three years.
Bill McBride, who writes the 2 newsletter, concludes that 3, the prices landlords advertise to new tenants, have likely bottomed. Much of his post is paywalled, so only part of his evidence is visible.
A turn, not a boom
The increase is tiny. As a rough calculation, 0.1% on $1,384 is about $1.40 a month. In practice, rents are flat, and they would still be falling after inflation if consumer prices are rising faster. The news is that the decline has stopped.
Why rents fell, and why that is changing
Apartment List blames the weak market on a historic surge in 4 construction, meaning buildings with several rental units. The boom peaked in 2024, when more than 600,000 new units reached the market, the most in a single year since 1986.
New buildings open with many empty units, and owners compete for tenants by holding down rents. That pressure can outlast the construction peak. 5, or finished units reaching the market, have slowed considerably since 2024 but remain fairly robust by historic standards, and the market had still been struggling to fill them.
Now the report says the 6, the share of units sitting empty, is gradually tightening, and occupancy reached an inflection point this year alongside rent growth. Fewer empty units give landlords less reason to discount.
The conflicting signal
Not every series agrees. McBride's next section is headed "7: 38th Consecutive Month with Year-over-year Decline in Rents," though its numbers are behind the paywall. Rent indexes use different samples and methods, so they can cross zero at different times, and a 0.1% reading could easily flip back. The visible text doesn't reconcile the two.
Why it matters
As general background, shelter makes up roughly a third of the 8, the main US inflation measure. That index covers all tenants, including those mid-lease, so new-lease rents tend to reach it about a year later. Flat asking rents have been a reason to expect slower shelter inflation, and a sustained rise would eventually weaken that pressure.
For renters, falling vacancy generally means less bargaining room over time. The excerpt gives no vacancy figure, regional breakdown or forecast, so the pace of any shift remains unknown.
The US rental market has reached a possible turning point. 1, a rental-listing site that publishes a monthly national rent report, puts its national median rent at $1,384, up 0.1% from a year earlier. It is the first positive year-over-year reading in more than three years. Bill McBride, author of the 2 newsletter, reviews rent and vacancy data each month, and his headline conclusion is that 3, the prices landlords advertise to new tenants, have likely bottomed.
The part of his post available to non-subscribers is short. It covers the Apartment List data and only the headline of a second data source. The rest is paywalled, so this write-up cannot assess his full evidence.
How small the change is
The news is the direction, not the size. As a rough calculation, a 0.1% rise on $1,384 is about $1.40 a month, or roughly $17 a year. That amounts to flat rents. If overall consumer prices are rising faster than that, rents are still falling in inflation-adjusted terms, even at the new positive reading.
"Bottomed" therefore means the decline has stopped. It does not by itself imply a strong rebound, and the visible portion of the post makes no forecast of how quickly rents might rise.
What caused the slump
Apartment List attributes the weak market of recent years to a historic surge in 4 construction, meaning buildings with several rental units. The boom peaked in 2024, when more than 600,000 new multifamily units reached the market, the most new supply in a single year since 1986.
The mechanism is straightforward. Each finished building adds empty units all at once, and its owner needs to fill them to cover costs. Owners compete for a limited pool of tenants by holding down or cutting rents, and that pressure spreads to nearby older buildings.
Rents can also stay soft after construction peaks. Apartment List says new deliveries, meaning finished units reaching the market, have slowed considerably since 2024 but remain fairly robust by historic standards. Even at what it calls the tail end of the boom, the market had still been struggling to absorb the new inventory, that is, to fill it with tenants.
The report says this is now changing. The 5, the share of units sitting empty, is gradually tightening, and occupancy has hit an inflection point this year alongside rent growth. Those two signals support each other: fewer empty units give landlords less reason to discount. The excerpt does not give a vacancy figure, so the size of the tightening can't be judged from it.
The data point that disagrees
McBride's next section is headed "6: 38th Consecutive Month with Year-over-year Decline in Rents." So one major series has turned slightly positive while another is still negative. The figures behind that heading are paywalled.
The disagreement isn't necessarily a contradiction. Realtor.com's rent report has generally focused on listings in the largest metro areas, while Apartment List publishes a national measure, and the two use different samples and methods. Indexes built differently can cross zero at different times, especially when one sits at just 0.1%. A small move in either series could change the sign. The visible text doesn't reconcile the two, and it's fair to treat "likely" in McBride's headline as doing real work.
Why this matters beyond renters
Rent has an outsized role in official inflation. Shelter is roughly a third of the 7, the main US measure of consumer inflation. That index measures rents paid by all tenants, including those in the middle of a lease, so changes in new-lease rents generally reach it with a lag of about a year.
That is general background rather than a claim made in the visible post, but it explains why economists watch this data. Falling or flat asking rents have been a reason to expect slower shelter inflation. If asking rents begin rising, that downward pressure would eventually weaken. At 0.1% growth, it would not yet add much upward pressure of its own.
For renters, the practical change would be gradual. A market with falling vacancies generally offers less negotiating room over time. For landlords and apartment investors, higher occupancy would help revenue before any large rent increases arrive. Neither the size nor the timing of these effects is established by the available data.
What remains open
Three questions can't be answered from the excerpt:
Durability. One reading just above zero is a thin base, and deliveries are still robust by historic standards.
Demand. The visible text explains the turn through supply and occupancy, with nothing on household formation, jobs or immigration, any of which could change how quickly units fill.
Geography. A national median can hide large differences between metro areas, and the available text doesn't break the figure down.
Remember
A positive rent reading can still mean falling real rents when growth is below overall inflation.
Housing gluts can outlast peak construction because finished buildings still need time to fill with tenants.
When rent series disagree near zero, wait for confirmation across several measures and months.